Business
Cut in Bank Charges: CBN Lists Penalties for Defaulters

- /home/rhoncare/pointblank.ng/wp-content/plugins/mvp-social-buttons/mvp-social-buttons.php on line 27
https://pointblank.ng/wp-content/uploads/2019/04/CBN-Gov.-new-1.jpg&description=Cut in Bank Charges: CBN Lists Penalties for Defaulters', 'pinterestShare', 'width=750,height=350'); return false;" title="Pin This Post">
- Share
- Tweet /home/rhoncare/pointblank.ng/wp-content/plugins/mvp-social-buttons/mvp-social-buttons.php on line 69
https://pointblank.ng/wp-content/uploads/2019/04/CBN-Gov.-new-1.jpg&description=Cut in Bank Charges: CBN Lists Penalties for Defaulters', 'pinterestShare', 'width=750,height=350'); return false;" title="Pin This Post">
The Central Bank of Nigeria (CBN) on Sunday reduced all bank charges, with some getting more than 50 per cent cut, with effect from January 1, 2020.
According to the apex bank, the decision, which came amid public outcry against multiplicity and value of the charges, is aimed at making financial services more accessible and affordable to various stakeholders in the economy.
The reviewed charges and fees for banking services are contained in the new “Guide to Charges by Banks, Other Financial and Non-bank Financial Institutions,” which now supersedes the 2017 version.
The CBN said the new charges were “arrived at after extensive consultations with stakeholders and the action is expected to enhance flexibility, transparency, and competition in the Nigerian banking industry.”
The guide stipulates a penalty of N2million per infraction or as may be determined by the CBN as a guard against excess, unapproved or arbitrary charges by banks and other financial institutions.
Besides, failure by any bank to comply with the CBN’s directive in respect of any infraction shall also attract a further penalty of N2million daily or as may be determined by the apex bank, until the directive is complied with.
To emphasise the seriousness of the new rule, the Director of Corporate Communications Department, CBN, Isaac Okorafor, said the banks had been directed to henceforth log every complaint received from their customers into the Consumer Complaints Management System (CCMS).
Additionally, they are to generate a unique reference code for each complaint lodged, which must be given to the customer.
“Failure to log and provide the code to the customer amounts to a breach and is sanctionable with a penalty of N1million per breach,” he said.
According to him, “this is the time financial services providers and their customers alike have to acquaint themselves with the provisions of the guide and be guided accordingly.”
Specifically, for cards linked to a savings account, the maintenance fee has been reduced to a maximum of N50 per quarter from N50 per month amounting to only N200 per annum instead of N600.
The guide has removed Card Maintenance Fee (CAMF) on all cards linked to current accounts. It also pegged a maximum of N1 per mile for customer-induced debit transactions on current accounts to third parties and transfers or lodgments to the customers’ current accounts in other banks.
There is now a reduction in the amount payable for cash withdrawals from other banks’ Automated Teller Machines (ATMs), known as Remote-on-Us, from N65 to N35.
Other reductions include Advance Payment Guarantee (APG), which is now pegged at a maximum of one per cent of the APG value in the first year and 0.5 per cent for subsequent years on contingent liabilities.
For all debit cards, a one-off charge at N1,000 applies to the issuance, irrespective of card type- regular or premium. The same one-off charge of N1,000 applies for the replacement of debit cards at the customer’s instance for loss, damage or expiry. Conversely, no charge shall be required for pre-paid card loading/unloading.
Okorafor explained that the current NIBSS Instant Payment charges applied to the use of Unstructured Supplementary Service Data (USSD), as purchase with cash-back will attract a charge of N100 per N20,000, subject to cumulative N60,000 daily withdrawal.
“There will be no more charges for reactivation or closure of accounts such as savings, current and domiciliary accounts, while status inquiry at the request of the customer (like confirmation letter, letter of non-indebtedness and reference letter) will now attract a fee of N500 per request.
“CBN carried out the review of the guide, which also prescribes charges permissible for other financial institutions and non-bank financial institutions, to align with market developments,” he added.
The Guardian


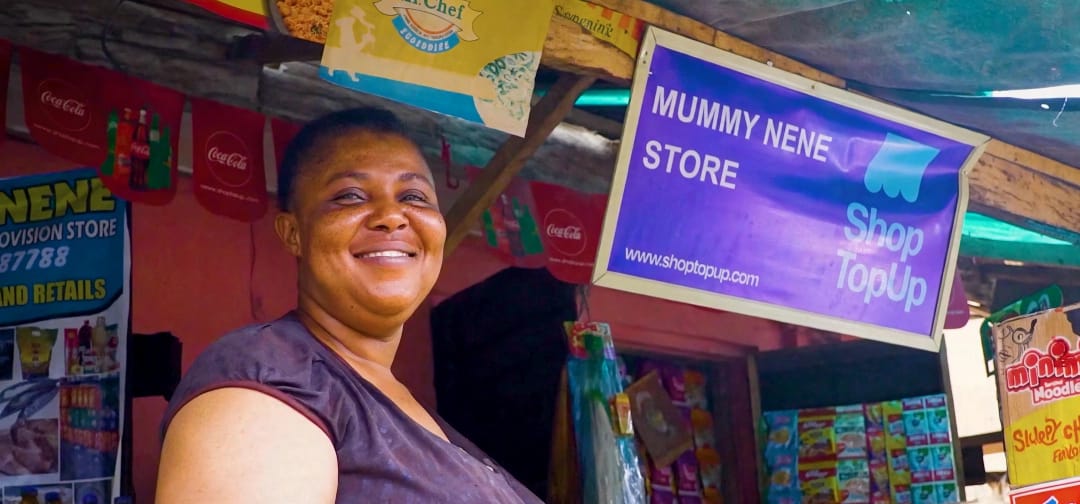
While conversations about the future of retail increasingly focus on supermarkets, shopping malls and online shopping platforms, millions of African consumers continue to rely on a more familiar and accessible business: the neighbourhood shop.
From small provision stores and corner shops to kiosks and informal retailers, these businesses remain an important part of everyday commerce, connecting communities to essential household products. However, behind their convenience lies a supply chain challenge that often limits their growth.
For many small retailers, sourcing products, managing inventory and securing enough working capital to keep their shelves stocked can be difficult. Fragmented distribution networks, multiple intermediaries and limited access to financing often make it harder for them to compete and expand.
Technology is beginning to offer a different possibility.
Digital platforms can simplify the way neighbourhood retailers purchase goods by connecting them more directly with manufacturers and distributors. They can streamline ordering, improve product availability and make inventory management more efficient.
Access to financial technology can further strengthen these businesses by helping eligible retailers secure the working capital required to replenish stock, respond to customer demand and grow sustainably.
One Nigerian technology company working to address these challenges is TradeDepot, which is using digital innovation to connect small retailers with manufacturers and distributors.
By making product sourcing and distribution more efficient, the company is helping to address some of the longstanding barriers facing small businesses in Africa’s retail sector.
However, scaling technology-driven solutions across a fragmented retail market requires more than innovation. It also demands significant investment.
This is where development finance and venture capital become important.
Through Boost Africa, the European Investment Bank (EIB) invested in Partech Africa Fund, a venture capital fund that subsequently backed TradeDepot. The investment illustrates how development finance can reach innovative African businesses through investment funds, providing capital to companies working to solve real economic challenges.
Boost Africa is a joint initiative of the European Investment Bank and the African Development Bank, with support from the European Union. The initiative supports African businesses and strengthens the continent’s entrepreneurial ecosystem by improving access to finance and opportunities for growth.
The wider significance of this investment goes beyond the technology platform itself. Strengthening neighbourhood retailers can contribute to more efficient supply chains, support small business growth and improve access to everyday consumer goods across communities.
For Africa, where small retailers remain central to local economies, the opportunity is substantial.
The future of retail may not necessarily involve replacing traditional neighbourhood shops with large supermarkets or online marketplaces. Instead, it could depend on equipping these existing businesses with better technology, stronger distribution networks and improved access to finance.
Ultimately, transforming retail may begin with something as familiar as the shop around the corner.
Boost Africa: From Capital to Impact.
Watch how TradeDepot is bringing commerce closer to communities through technology and investment
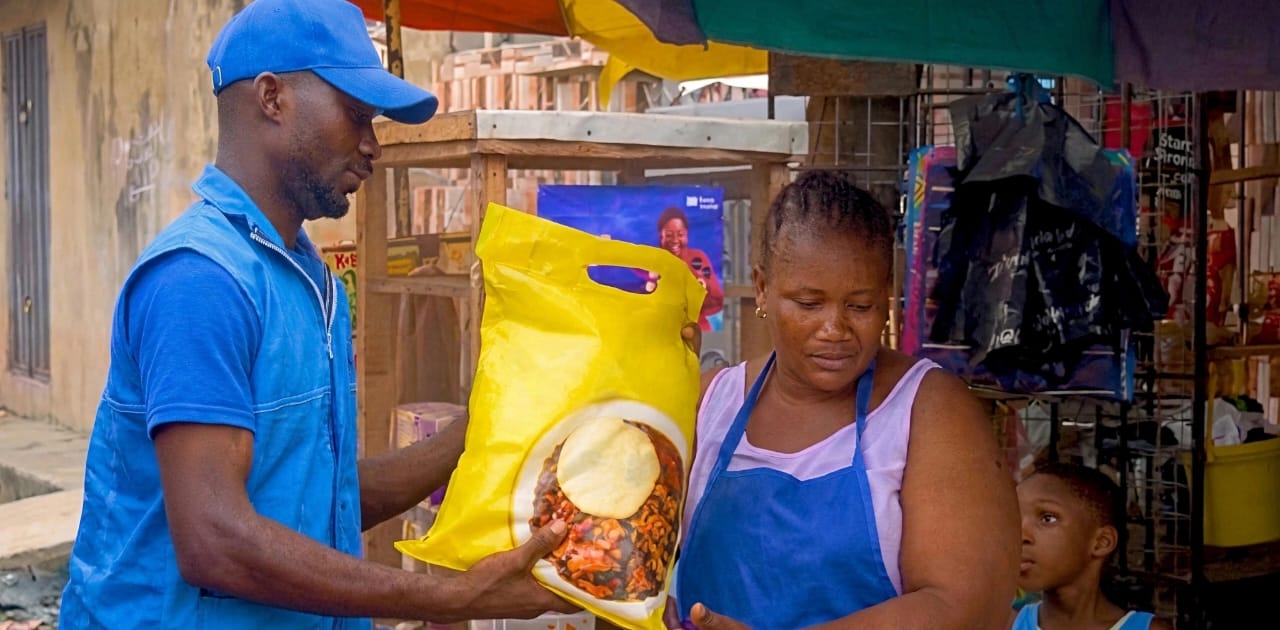
Ever wondered how the products on your neighbourhood shop shelves get there? Behind everyday purchases is a supply chain that can be costly, complex and inefficient, particularly for small retailers.
Nigerian technology company TradeDepot is changing this process by using technology to connect small retailers with manufacturers and distributors, making it easier for shop owners to order and receive the goods they need.
But transforming retail distribution takes more than an innovative idea. It requires investment to build, expand and scale.
Through Boost Africa, the European Investment Bank (EIB), alongside the African Development Bank and with support from the European Union, is helping strengthen the financing ecosystem for innovative African businesses.
One example is the EIB’s investment in Partech Africa Fund, which subsequently backed TradeDepot, helping channel capital into a Nigerian business working to improve how goods move from suppliers to neighbourhood shops.
The impact goes beyond technology. More efficient distribution can help small retailers access inventory, strengthen connections between manufacturers and suppliers, and bring commerce closer to the communities they serve.
Ultimately, TradeDepot’s story demonstrates how investment can go beyond funding to support stronger businesses, more efficient markets and opportunities for small retailers.
Boost Africa: From Capital to Impact.
Watch how TradeDepot is bringing commerce closer to communities.
▶ https://www.youtube.com/watch?v=zw9t2asF9Pc
Business
Beyond University Degrees: How ChipMango is Preparing African Engineers for Global Tech Industry
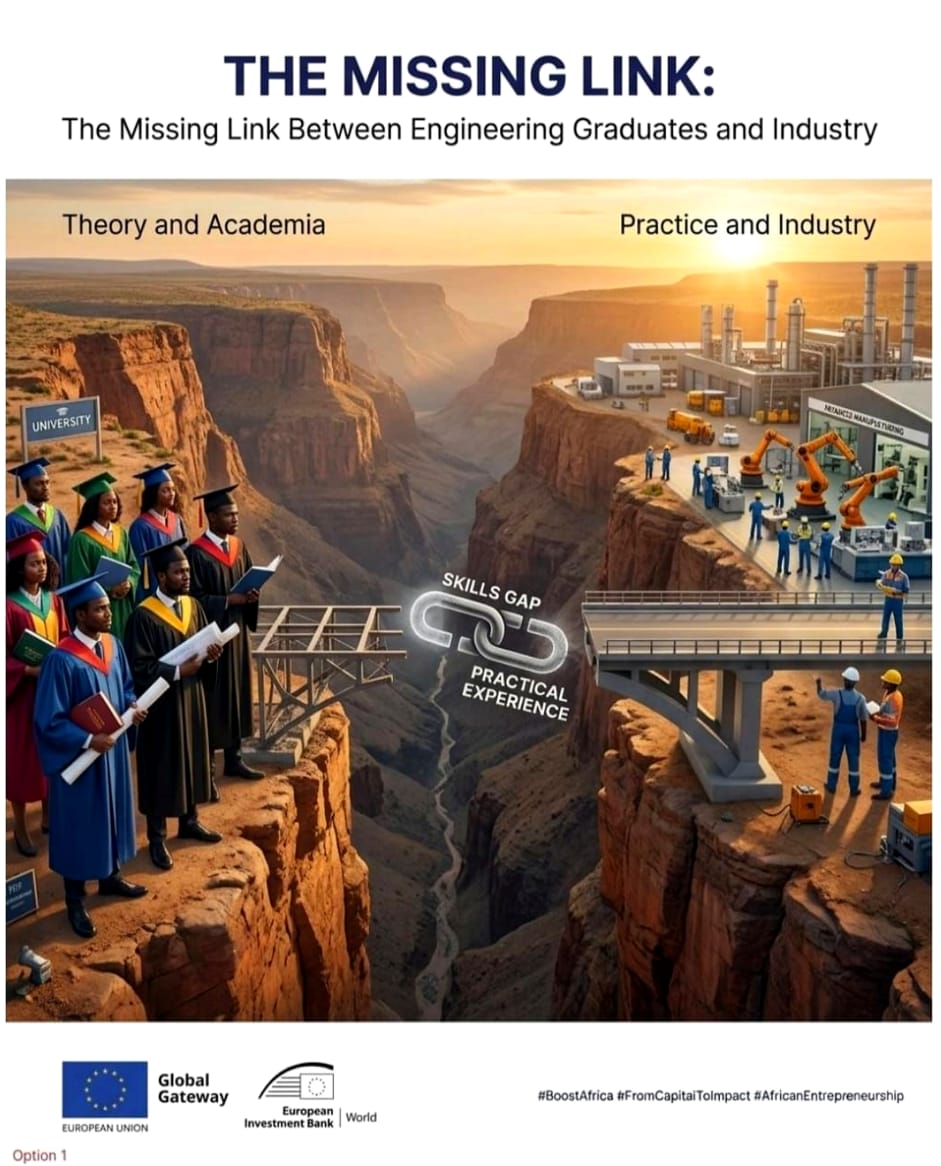
A university degree is a starting point, but practical industry experience can make all the difference.
Nigerian technology company ChipMango is bridging the gap through specialised semiconductor training and real-world chip design and verification projects, preparing African engineers for opportunities in the global technology industry.
Through Boost Africa, the EIB, AfDB and EU are strengthening the investment ecosystem supporting innovative African businesses.
Watch the video to discover how ChipMango is connecting engineering talent to real industry opportunities.
Watch the video: