Business
FirstBank’s ₦1trn Digital Loan Disbursement Milestone and New Era of Inclusive Lending in Nigeria

- /home/rhoncare/pointblank.ng/wp-content/plugins/mvp-social-buttons/mvp-social-buttons.php on line 27
https://pointblank.ng/wp-content/uploads/2024/05/Segun-Alebiosu-Ag.-CEO-FirstBank-1.jpg&description=FirstBank’s ₦1trn Digital Loan Disbursement Milestone and New Era of Inclusive Lending in Nigeria', 'pinterestShare', 'width=750,height=350'); return false;" title="Pin This Post">
- Share
- Tweet /home/rhoncare/pointblank.ng/wp-content/plugins/mvp-social-buttons/mvp-social-buttons.php on line 69
https://pointblank.ng/wp-content/uploads/2024/05/Segun-Alebiosu-Ag.-CEO-FirstBank-1.jpg&description=FirstBank’s ₦1trn Digital Loan Disbursement Milestone and New Era of Inclusive Lending in Nigeria', 'pinterestShare', 'width=750,height=350'); return false;" title="Pin This Post">
For decades, Nigeria’s credit system posed significant challenges for small businesses and low-income earners, who often struggled to qualify for loans. Traditional banks demanded collaterals, guarantors, and endless paperwork, effectively shutting out a large portion of the population working in the informal economy.
FirstBank’s digital lending model flipped the script. With the launch of its digital lending model, the bank eliminated collateral requirements and slashed approval times from weeks to under five minutes. Loans now flow through multiple channels including *894# (the Bank’s USSD service), FirstMobile, LitApp, and the FirstMonie agent network, reaching market traders, civil servants, rural farmers and everyday individuals.
When FirstBank disbursed its first instant digital loan in August 2019, the transaction seemed like a bold experiment in tech-driven finance. Today, just six years later, the 131-year-old financial institution has announced cumulative disbursements of over N1 trillion in digital loans, a milestone that redefines the scale of retail digital lending in Nigeria’s financial services industry. This achievement reflects a deep shift in the way and manner Nigerians (salary earners, small and medium scale entrepreneurs, and the financially excluded) access loans. Credit, once a privilege for the wealthy or formally employed, is now a tap away for millions of Nigerians. FirstBank is helping people to grow their businesses, seize opportunities, and stay afloat in challenging times.
The numbers tell a compelling story: over 1.5 million unique borrowers have accessed loans through FirstBank’s digital platforms. For a banking system historically constrained by bureaucracy, and rigid risk models, the existence of collateral-free, instant digital loans comes as a relief. FirstBank has tapped into an unmet demand that traditional lending channels have struggled to capture. Its digital lending ecosystem, designed with Artificial Intelligence and Machine Learning, is tailored to assess high-risk segments that conventional credit scoring often overlooks.
In Nigeria, where over 40 percent of the adult population are still underbanked or completely unbanked, FirstBank is reshaping what inclusion looks like. The issue is not that Nigerians lack ambition or the ability to repay loans; it is that traditional banking systems have long struggled to assess their creditworthiness. Legacy models simply could not capture the financial realities of people outside the formal economy.
FirstBank is rewriting that narrative. Through a range of digital loan products (FirstAdvance for salary earners, FirstCredit for individuals without formal employment, and Agent Credit for micro-businesses operating within the FirstMonie Agent network), the bank is showing how financial inclusion can be scaled with smart, data-driven tools. These products are tailored to meet people where they are, using technology to bridge gaps that paperwork once made impassable.
FirstBank’s digital lending strategy deeply aligns with Nigeria’s broader financial inclusion goals. The 2023 EFInA Survey Report on Access to Financial Services in Nigeria (A2F) shows that 64 percent of the Nigerian population is now formally included in the financial system. Much of this progress is thanks to the increased adoption of mobile money and digital financial services, which are making banking accessible even in the most remote corners of the country.
The implications for micro, small, and medium enterprises (MSMEs) are profound. According to the Small and Medium Enterprises Development Agency of Nigeria (SMEDAN), MSMEs contribute nearly 50 percent to the country’s GDP and employ over 80 percent of the labour force, yet access to formal credit remains one of their greatest constraints. Through Agent Credit, FirstBank empowers small traders, artisans, and shopkeepers, many in areas far from any bank branch, with quick, affordable capital. This redistribution of financial access fosters economic participation and resilience at the grassroots.
The significance of this model extends beyond Nigeria. Across Africa, where an estimated 350 million adults lack access to formal financial services, FirstBank’s model offers a blueprint. African banks can leverage existing mobile adoption, behavioural data, and agent networks to build credit ecosystems suited to local realities, utilising digital lending as a bridge between exclusion and empowerment. It is proof that banks can be more than just gatekeepers; they can be catalysts for inclusive growth.
Industry analysts see FirstBank’s digital lending milestone as part of a broader evolution in Nigeria’s digital economy. In the past decade, the proliferation of mobile banking and agent banking has pushed the boundaries of accessibility. Yet, access to credit has remained a stubborn bottleneck. While savings and payment platforms grew quickly, lending stayed cautious. Banks were held back by the risk of defaults, weak identification systems, and limited credit histories. FirstBank is showing how that equation can be changed. By using data aggregation, alternative credit scoring models, and digital channels, the bank is unlocking new ways to assess risk and extend credit more confidently.
However, scaling digital credit also raises questions about sustainability and customer protection. In Kenya, for example, the rapid growth of digital loans over the past decade led to concerns about over-indebtedness, data privacy, and predatory lending practices by unregulated operators. Nigeria’s regulatory environment will need to balance innovation with safeguards, ensuring that customers are included and protected. FirstBank is ahead on this, leveraging AI not only for loan approvals but also for proactive risk management, ensuring defaults are minimised and repayment behaviour is nurtured responsibly.
Another dimension is the competitive landscape. Many fintech lenders have built reputations on offering fast, collateral-free loans. Yet, their model has often been characterised by exploitative interest rates and coercive repayment tactics, and regulatory headwinds. FirstBank, with its balance sheet strength, established reputation, and nationwide presence, has a competitive edge in blending the agility and flexibility of fintech with the resilience of traditional. With over N1 trillion digital loans successfully processed, the bank demonstrates the ability to serve Nigerians with speed while providing a level of institutional trust many customers still value.
The milestone also reflects a cultural shift in how Nigerians relate to their banks. For decades, traditional banks were perceived as conservative institutions, more interested in corporate customers than on individuals struggling with school fees, rent, or working capital for their shops. By embedding loan access into its digital channels and the FirstMonie Agent network, FirstBank has repositioned itself as a partner in everyday life. Whether customers use smartphones or basic feature phones, they now have equal access to credit and are no longer sidelined by technology gaps or administrative hurdles.
From an economic perspective, the ripple effects of FirstBank’s digital lending ecosystem are far-reaching. Beyond consumption smoothing for households, instant digital loans catalyse economic activity in local markets. Traders can restock quickly, farmers can purchase farm inputs when they are needed, and artisans are able to meet unexpected orders. When aggregated, these micro-impacts contribute to broader productivity and growth, helping to stabilise the informal economy that forms the lifeblood of local commerce.
As FirstBank marks this landmark achievement, it also confronts the responsibility that comes with scale. Digital lending at this magnitude is not merely a product line; it is a public utility shaping how millions experience financial security. Sustaining this momentum will require continuous innovation and a firm focus on customer empowerment, values that are deeply ingrained in the bank’s DNA.


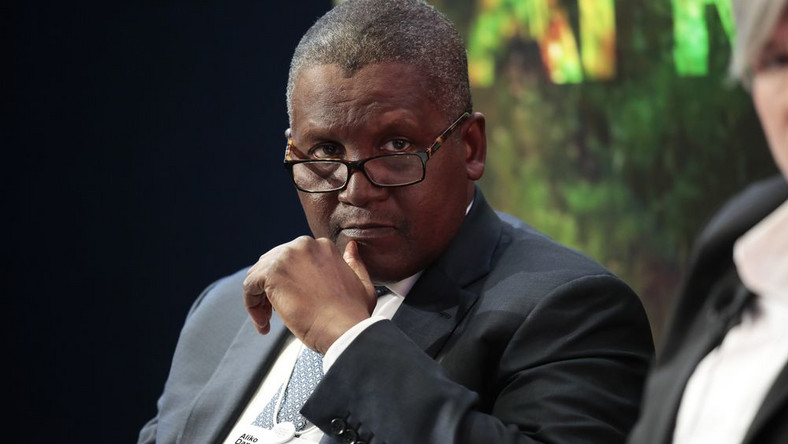
Ugandan President, Yoweri Museveni, has met with Nigerian billionaire Aliko Dangote at State House, Entebbe, to discuss investment opportunities in energy, petroleum, agriculture, and mining. A key area of interest was the fertilizer industry, aimed at enhancing regional food security.
According to Museveni, the meeting highlighted progress on Uganda’s crude oil refinery project, a joint venture with Alpha MBM from the United Arab Emirates, with an initial capacity of 60,000 barrels per day.
This meeting follows Dangote’s recent launch of the multi-billion-dollar Dangote East Africa Petroleum Refinery in Lamu County, Kenya.
Museveni, who attended the occasion, welcomed the development, emphasising Africa’s shift from exporting raw materials to local processing.
Museveni welcomed the development, noting that Africa is gradually moving away from decades of exporting raw materials instead of processing them locally.
“I am happy to see Africa waking up and moving away from the 70-year betrayal of exporting raw materials,” President Museveni said. “Dangote, who started as an importer and has become a national and continental asset, is a good example of the transformation we need.”
Addressing regional energy infrastructure needs, Museveni clarified that Kenya’s new mega-refinery would not conflict with Uganda’s own downstream ambitions or existing cross-border partnerships.
“Uganda’s refinery will be built, and our cooperation with Tanzania on Tanga stands. There is no harm in having more refineries in the region. What Africa needs is value addition, industrialisation and bigger integrated markets,” Museveni noted, adding: “East African political integration must ultimately be treated as a matter of strategic survival.”
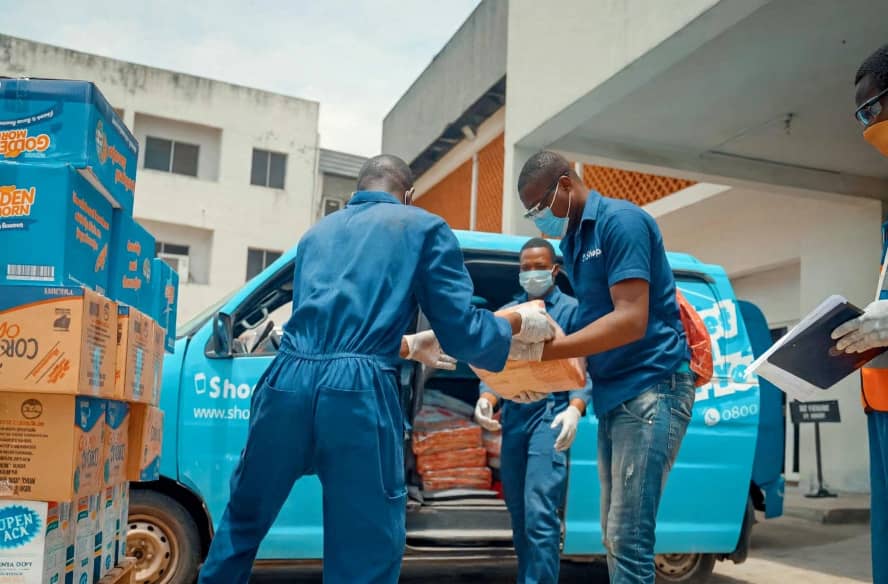
Africa’s informal retail sector presents a major opportunity for economic growth, as technology companies explore ways to improve how small businesses source products, manage supplies and serve consumers.
Nigerian technology company TradeDepot is addressing the challenge by connecting neighbourhood shops, kiosks, market stalls and small provision stores with manufacturers and distributors through digital solutions.
The initiative targets a largely underserved segment of Africa’s retail industry, where many small businesses face difficulties accessing reliable suppliers, efficient distribution networks and appropriate financial services.
By improving access to products and simplifying procurement, TradeDepot aims to help retailers reduce supply-chain challenges and focus more on serving customers.
The impact could extend beyond individual businesses to manufacturers and distributors through improved market access, more efficient product distribution and stronger connections with local communities.
The company’s growth has also received institutional investment support. Through its Boost Africa initiative, the European Investment Bank (EIB) invested €10 million in Partech Africa Fund, which subsequently backed TradeDepot.
Boost Africa, a partnership supporting innovative African businesses, demonstrates how investment capital can help technology companies develop solutions for underserved markets.
As Africa’s retail landscape evolves, the informal sector is increasingly attracting attention as a major driver of commerce, employment and enterprise development.
TradeDepot’s approach highlights the potential of using technology and investment to strengthen the small businesses already supplying everyday goods to millions of African consumers.
Watch the video: https://www.youtube.com/watch?v=zw9t2asF9Pc
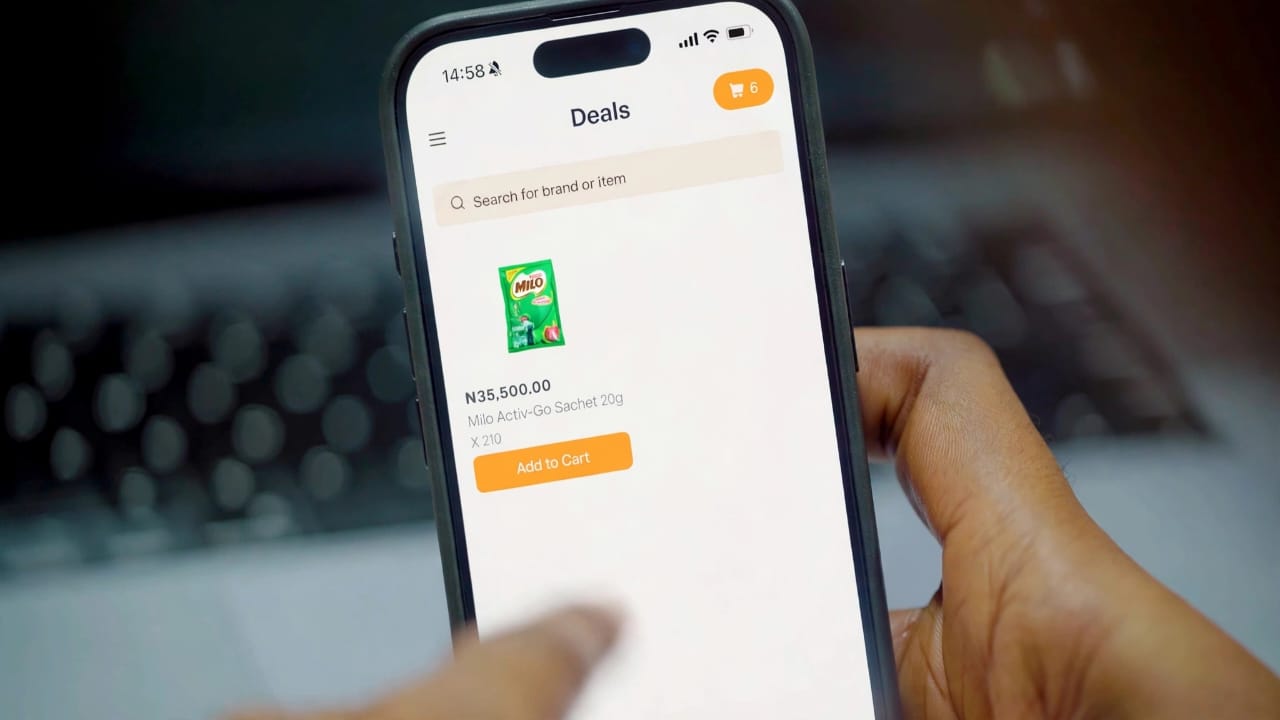
From manufacturers and distributors to neighbourhood retailers, technology and investment are reshaping the systems that move products across African markets.
When a customer walks into a neighbourhood shop and finds exactly what they need, the transaction may appear simple. But behind that everyday purchase is a complex network of businesses, people and systems working together to make it happen.
Manufacturers produce the goods, distributors move them through supply channels, logistics providers handle transportation, and retailers ensure products reach consumers. Payment systems and financing also play important roles in keeping this commercial ecosystem running.
However, across many African markets, the infrastructure connecting these players remains fragmented, creating challenges that affect how businesses operate and how efficiently products reach consumers.
For small retailers, sourcing products can involve dealing with multiple intermediaries, navigating inefficient distribution networks and managing unpredictable supplies. Limited access to working capital can further complicate inventory management, making it difficult to keep essential products consistently available.
These challenges point to a bigger issue: the future of commerce is not just about selling more products or creating new shopping experiences. It is also about strengthening the infrastructure that makes buying, selling and distribution possible.
Technology is increasingly becoming part of the solution.
Digital platforms can connect retailers with manufacturers and distributors, simplify ordering processes and improve visibility across supply networks. When combined with efficient logistics and access to financing, these innovations can help businesses manage inventory, improve distribution and build stronger commercial relationships.
This is the space in which TradeDepot, a Nigerian technology company, is making its contribution. By using technology to connect small retailers with manufacturers and distributors, the company is helping address some of the structural challenges within traditional retail supply chains.
Its approach reflects a broader opportunity in Africa’s digital transformation: moving beyond solutions that simply improve the customer experience to innovations that strengthen the underlying systems supporting businesses, distribution networks and economic activity.
Investment also plays a critical role in making this transformation possible.
Through Boost Africa, the European Investment Bank (EIB) invested €10 million in Partech Africa Fund, which subsequently backed TradeDepot. The investment demonstrates how development finance and venture capital can support African technology companies working to address fundamental market challenges.
Beyond supporting individual businesses, such investments can contribute to the development of stronger commercial networks, improved infrastructure and innovative solutions that make entire economic value chains more efficient.
Ultimately, a thriving retail sector needs more than shops and customers. It needs reliable supply chains, efficient distribution networks, accessible financing and technology that connects every part of the journey.
Because the future of commerce will not be determined only by what businesses sell, but also by how effectively the systems behind those transactions work.
Boost Africa: From Capital to Impact.
Watch how TradeDepot is bringing commerce closer to communities through technology and the Boost Africa initiative: