Business
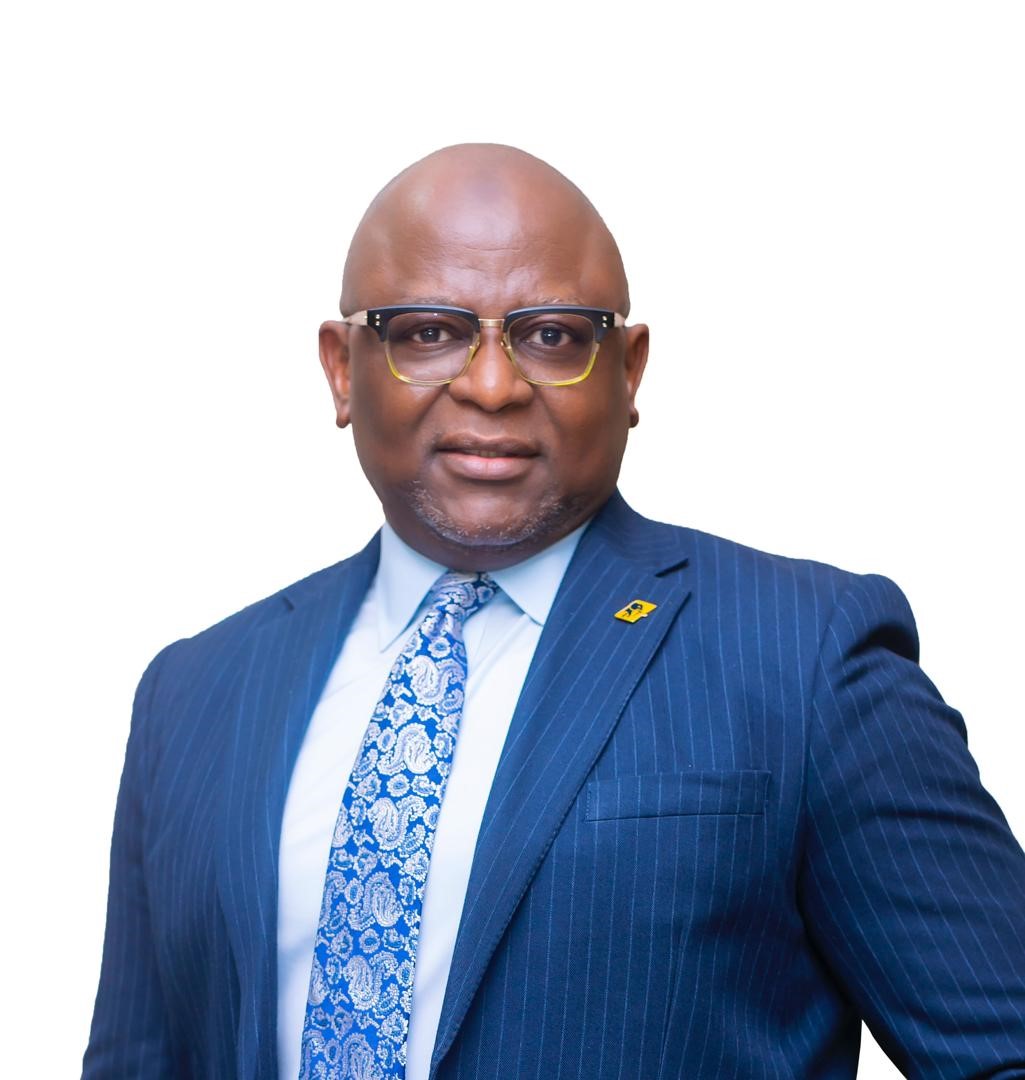
How to Do Well by Doing Good – Adesola Adeduntan, CEO, FirstBank

- /home/rhoncare/pointblank.ng/wp-content/plugins/mvp-social-buttons/mvp-social-buttons.php on line 27
https://pointblank.ng/wp-content/uploads/2020/03/Dr.-Adesola-Adeduntan-FirstBank-CEO-1000x600.jpg&description=How to Do Well by Doing Good – Adesola Adeduntan, CEO, FirstBank', 'pinterestShare', 'width=750,height=350'); return false;" title="Pin This Post">
- Share
- Tweet /home/rhoncare/pointblank.ng/wp-content/plugins/mvp-social-buttons/mvp-social-buttons.php on line 69
https://pointblank.ng/wp-content/uploads/2020/03/Dr.-Adesola-Adeduntan-FirstBank-CEO-1000x600.jpg&description=How to Do Well by Doing Good – Adesola Adeduntan, CEO, FirstBank', 'pinterestShare', 'width=750,height=350'); return false;" title="Pin This Post">
By Omar Ben Yedder
I travel to meet Dr Adesola Adeduntan in Edinburgh, where he has been invited to give a keynote address at the Edinburgh School of Business about the role of financial institutions in driving financial inclusion.Fittingly, as you land in Edinburgh, you are greeted by billboards from different investment funds advertising their credentials in responsible and sustainable investment and how environmental, social and governance (ESG) considerations underpin their activities.
With economists and politicians questioning capitalism and the Western liberal model, today the emphasis is very much on a stakeholder-based approach, whereby growth and prosperity is more equally attributed and takes into consideration the needs of the wider community. Sustainable investment has become de rigueur among corporate jargon.
Dr Adesola Kazeem Adeduntan, CEO of First Bank of Nigeria, is a veteran in the Nigerian banking and corporate world. His overriding message, clearly expressed throughout his interview responses, and also at the various talks he gave during the day (at the Business School and at a law firm), is on the importance of doing good if you’re to do well – financially – in Nigeria and indeed, Africa.
A telling sign
FirstBank is actually the oldest bank in Africa. It was established in Lagos in 1894 as the Bank of British West Africa. Last year it celebrated its 125th anniversary. It is also the biggest bank in Nigeria in terms of assets and branch network.
For Adeduntan, a veterinary doctor by training, it becomes clear, once we have settled down for our discussion, that the institution’s longevity is a telling sign: it not only proves the bank’s resilience, it also shows that it has the right structures in terms of governance and the right business model, with the country’s development at its core. The theme of the anniversary celebrations was about how the bank has been woven into the fabric of Nigerian society.
The clear message to the industry is that while it is possible to make a quick buck, you can only enjoy the sort of longevity it has if you conduct your business with the interests of the country at heart.
Nonetheless, it’s apparent Adeduntan does not want to dwell too long on past glories. Using the analogy of a car, he says that there is a reason why the windshield is large whilst the rear-view mirror is small.
The challenge of fintech
As in most sectors, traditional ways of doing business have been coming under increasing disruption from ever-evolving technology. The banking industry is no exception and seems to be under siege from an expanding fintech onslaught.
I ask him if he is worried that non-financial companies will be entering the banking sector, especially given the recent change in regulation by the Central Bank that allows non-traditional finance institutions, namely mobile operators, to enter the fray.
He says he is not worried as his bank has one of the best defined strategies when it comes to financial inclusion and that it has the largest digital banking network in Nigeria.
Much of this has been developed through the bank’s FirstMonie Agents system: 46,000 agents represent the bank across the country. Currently, 9m customers transact on their USSD platform (by mobile phone, both smart and analogue) in addition to 3m customers transacting on the FirstMobile platform.
The agent network, the biggest of its kind in the country, enables the bank to provide services to the most remote rural communities; and because it doesn’t need to have an extensive branch network, it means that these services can be supplied at a fraction of the cost of a ‘legacy’ banking model.
Financial deepening
Adeduntan prefers to use the phrase ‘financial deepening’ when talking about the unbanked. Financial inclusion has increased from the low 20s to approximately 40% in Nigeria over the past seven years and is expected to double to the mid-80s within the next five years.
He says ‘financial deepening’ occurs when financial inclusion starts playing an important role in economic development. It’s about layering additional products on the current agency banking network – services such as micro-credit, micro-insurance and micro-pension.
The aim is to provide value-added services whilst at the same time increasing the savings rate; this aspect, which is critical in driving investment rates, has been one factor behind Asia’s rapid growth.
It is in this area, he says, that the bank has a vital role to play and a distinct advantage over new entrants. Technology, he emphasises, will play a crucial part in broadening financial inclusion. In addition, it is important to partner and collaborate with different stakeholders such as NGOs and other organisations dealing with the bottom of the pyramid, to help them reach out to different groups and also improve financial literacy.
Last year saw a boom in venture capital investment into Nigeria. For example, $400m was invested in a number of fintech start-ups during November alone. Is he not worried that these fintech players, with their lower cost base and ability to use technology, AI and big data to overcome traditional hurdles, are going to take the majority share of the pie when it comes to servicing the unbanked?
He says that will only be the case if the banks do not manage to reinvent themselves. In Edinburgh, he actually spent a large part of his day visiting tech hubs around the university in the city and speaking to fintech companies. FirstBank, he adds, has a number of partnerships with fintechs as well as its own Digital Laboratory developing new solutions for the bank.
Nevertheless, he firmly believes that the ‘legacy banks’ will still continue to play a very central role, especially “in this part of the world where banks are quite dominant and they have significant buying power”.
In terms of settlements and deposits, he sees many of these new players as partners they can work with, even if in some areas they will be competitors.
Scope for growth
Despite the impressive strides made by the banking sector in Nigeria, Adeduntan believes there is still a massive scope for growth for the sector. He points out that none of the country’s top banks have made the Top 10 Banks in Africa list, despite Nigeria being the continent’s largest economy.
He thinks that with the signing of the African Continental Free Trade Agreement, “we are entering a very interesting period for the banking sector, not only in Nigeria but Africa in general”.
On the domestic front, does he expect further consolidation? “Within certain thresholds,” he answers. “Anything that would allow the strengthening of the entire banking sector, I am sure the Governor of the Central Bank would be positive about.”
He also points to demographics and the high rate of the unbanked as great opportunities for the growth of the sector continentally. “According to UNICEF, two billion babies will be born in Africa in the next 30 years,” he says. “And in places like DRC [where FirstBank has a presence] financial penetration is as low as 5%.” Put the two sets of figures together and, in theory at least, you get vast opportunity. But he adds the all-important caveat that demographics are only good if managed properly.
Supporting national champions
It hasn’t all been plain sailing for the bank, however. Adeduntan inherited a bank with several large exposures in the oil & gas and energy sectors, at a time when the oil & gas prices fell considerably, resulting in the devaluation of the naira against the dollar.
He says his management weathered the storm, reduced NPL levels to under double digits, and has strengthened the risk infrastructure, thus enabling the bank to better deal with cyclical downturns in future.
Discussing the role of large companies in the commercial landscape, Adeduntan says it is essential to have big banks like FirstBank, just as it is vital to have national champion companies that have the scale and wherewithal to make transformative investment. Such companies require financial institutions of similar scale to support them. The Dangote Group’s investment into what will become the continent’s largest oil refinery is a case in point, he adds.
Role of the Central Bank
We move on to the regulator and the role of the Central Bank. Does he think that it is too interventionist, dictating how much banks should lend, where they should place their assets?
Adeduntan refused to be drawn into criticism of the regulator, with whom he says he, and other bank CEOs, have a strong relationship. But he did say that the role of a central bank in the development of an emerging economy is clearly different from the role of a central bank in a developed economy.
“It is not unusual that the Central Bank intervenes in critical sectors allied to the loan to deposit ratio. It’s about economic growth; it’s about development; it’s about channelling credit in sectors that are very important for the national economy.
“Let us take agriculture – again, we are one of the biggest lenders into that sector. We found the Central Bank intervention in some of those critical sectors extremely useful and not just for us as a bank, but for the country as a whole. When you look at intervention in agriculture, you have to put it in the context of the size of the population. Nigeria is a country of 200m people today. The business of feeding 200m people is a strategic business. Everything that is being done to ensure that at least we are self-sufficient in food production is strategically important. We find the Central Bank intervention in those areas quite useful and of national importance.”
He reflected the positive attitude of many Nigerian entrepreneurs to the country’s future. He says he has a lot of time for the Economic Advisory Council – composed of credible business leaders and economists – that has been put together by President Muhammadu Buhari. And despite reports that the government is not economy-minded, he thinks that it is a pro-business government.
Ethical banking
It is nearly 10.00 in the evening when we finish our talk, his day having started at 07.30am. We go back to sustainability and the role of financial services to make sure they are lending to institutions that are ethical about their business and operating in a sustainable manner.
He says that the journey has started even if it is still early days. “But ultimately,” he says, “this is where we are headed. The Nigerian Sustainable Banking Principle speaks to this particular question. I think it’s evident from the points that I’ve made today, you can say that FirstBank is a bank that is happy to forego a few basis points in terms of its net margins, if that means it is contributing to development in a more ethical and sustainable way.
“We’ve always made a point that profitability is very important for us at FirstBank, but economic growth and national development is equally very important and speaks to the sustainability question.”


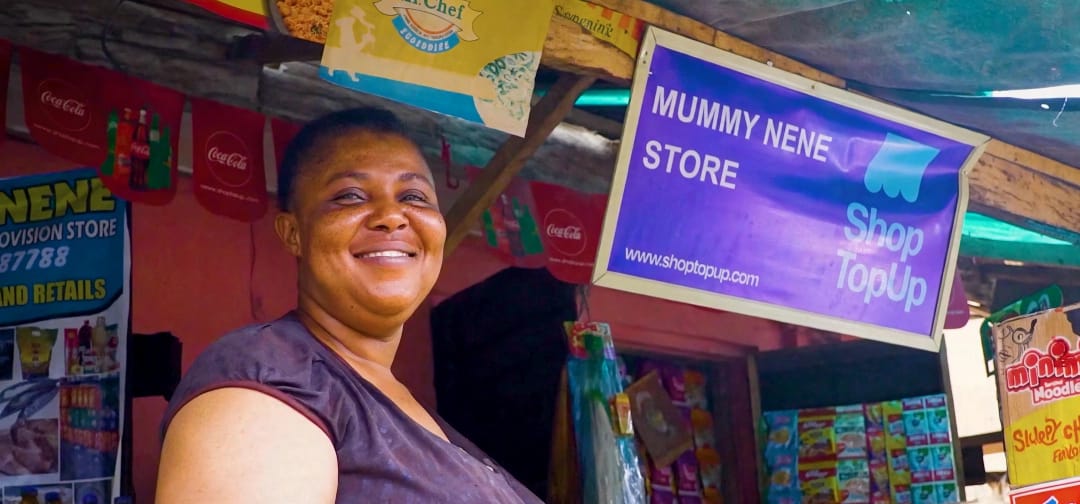
While conversations about the future of retail increasingly focus on supermarkets, shopping malls and online shopping platforms, millions of African consumers continue to rely on a more familiar and accessible business: the neighbourhood shop.
From small provision stores and corner shops to kiosks and informal retailers, these businesses remain an important part of everyday commerce, connecting communities to essential household products. However, behind their convenience lies a supply chain challenge that often limits their growth.
For many small retailers, sourcing products, managing inventory and securing enough working capital to keep their shelves stocked can be difficult. Fragmented distribution networks, multiple intermediaries and limited access to financing often make it harder for them to compete and expand.
Technology is beginning to offer a different possibility.
Digital platforms can simplify the way neighbourhood retailers purchase goods by connecting them more directly with manufacturers and distributors. They can streamline ordering, improve product availability and make inventory management more efficient.
Access to financial technology can further strengthen these businesses by helping eligible retailers secure the working capital required to replenish stock, respond to customer demand and grow sustainably.
One Nigerian technology company working to address these challenges is TradeDepot, which is using digital innovation to connect small retailers with manufacturers and distributors.
By making product sourcing and distribution more efficient, the company is helping to address some of the longstanding barriers facing small businesses in Africa’s retail sector.
However, scaling technology-driven solutions across a fragmented retail market requires more than innovation. It also demands significant investment.
This is where development finance and venture capital become important.
Through Boost Africa, the European Investment Bank (EIB) invested in Partech Africa Fund, a venture capital fund that subsequently backed TradeDepot. The investment illustrates how development finance can reach innovative African businesses through investment funds, providing capital to companies working to solve real economic challenges.
Boost Africa is a joint initiative of the European Investment Bank and the African Development Bank, with support from the European Union. The initiative supports African businesses and strengthens the continent’s entrepreneurial ecosystem by improving access to finance and opportunities for growth.
The wider significance of this investment goes beyond the technology platform itself. Strengthening neighbourhood retailers can contribute to more efficient supply chains, support small business growth and improve access to everyday consumer goods across communities.
For Africa, where small retailers remain central to local economies, the opportunity is substantial.
The future of retail may not necessarily involve replacing traditional neighbourhood shops with large supermarkets or online marketplaces. Instead, it could depend on equipping these existing businesses with better technology, stronger distribution networks and improved access to finance.
Ultimately, transforming retail may begin with something as familiar as the shop around the corner.
Boost Africa: From Capital to Impact.
Watch how TradeDepot is bringing commerce closer to communities through technology and investment
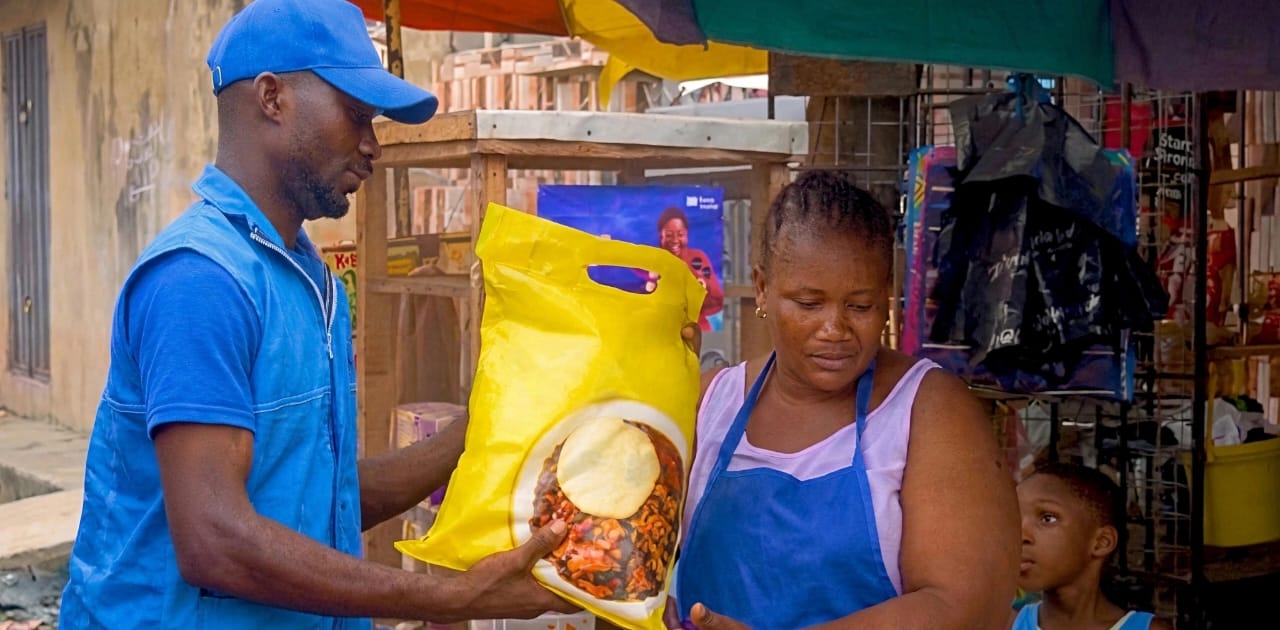
Ever wondered how the products on your neighbourhood shop shelves get there? Behind everyday purchases is a supply chain that can be costly, complex and inefficient, particularly for small retailers.
Nigerian technology company TradeDepot is changing this process by using technology to connect small retailers with manufacturers and distributors, making it easier for shop owners to order and receive the goods they need.
But transforming retail distribution takes more than an innovative idea. It requires investment to build, expand and scale.
Through Boost Africa, the European Investment Bank (EIB), alongside the African Development Bank and with support from the European Union, is helping strengthen the financing ecosystem for innovative African businesses.
One example is the EIB’s investment in Partech Africa Fund, which subsequently backed TradeDepot, helping channel capital into a Nigerian business working to improve how goods move from suppliers to neighbourhood shops.
The impact goes beyond technology. More efficient distribution can help small retailers access inventory, strengthen connections between manufacturers and suppliers, and bring commerce closer to the communities they serve.
Ultimately, TradeDepot’s story demonstrates how investment can go beyond funding to support stronger businesses, more efficient markets and opportunities for small retailers.
Boost Africa: From Capital to Impact.
Watch how TradeDepot is bringing commerce closer to communities.
▶ https://www.youtube.com/watch?v=zw9t2asF9Pc
Business
Beyond University Degrees: How ChipMango is Preparing African Engineers for Global Tech Industry
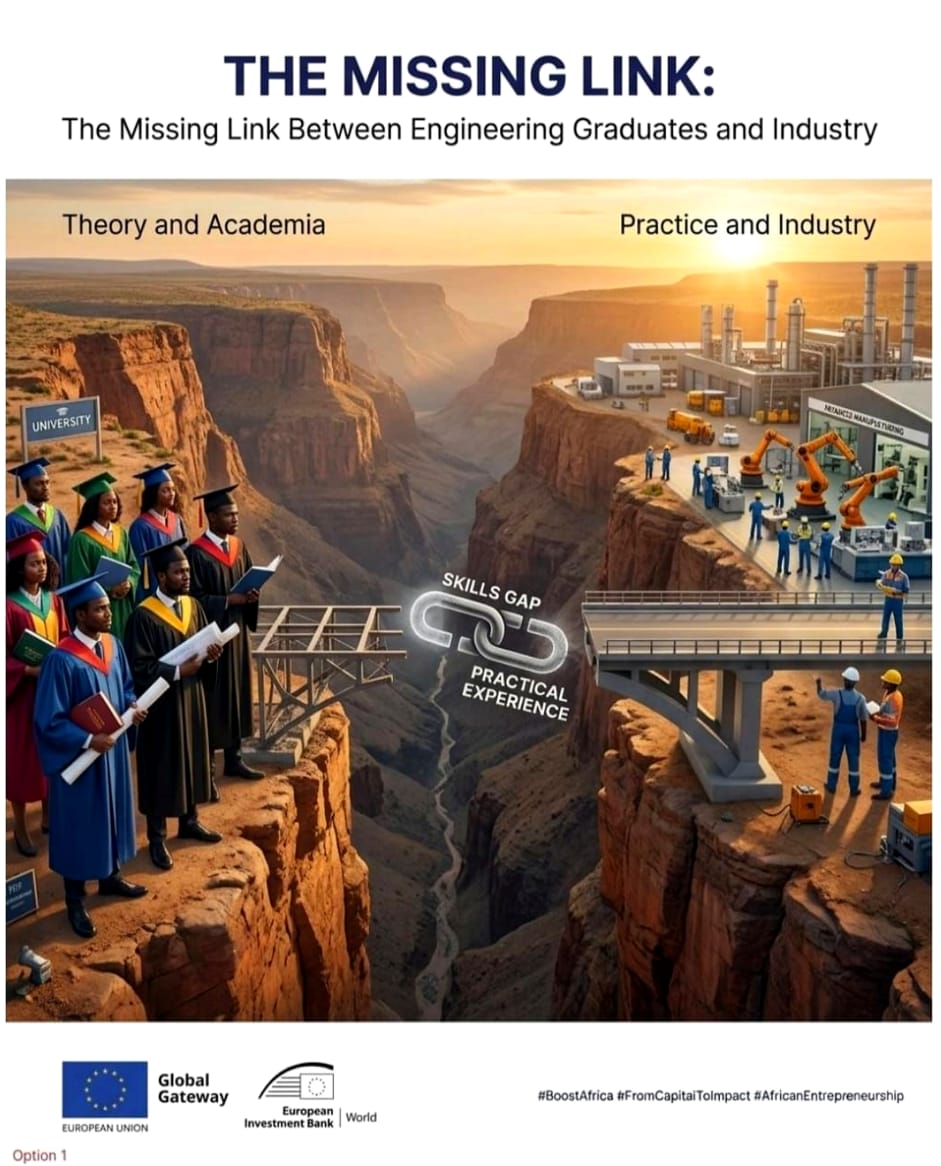
A university degree is a starting point, but practical industry experience can make all the difference.
Nigerian technology company ChipMango is bridging the gap through specialised semiconductor training and real-world chip design and verification projects, preparing African engineers for opportunities in the global technology industry.
Through Boost Africa, the EIB, AfDB and EU are strengthening the investment ecosystem supporting innovative African businesses.
Watch the video to discover how ChipMango is connecting engineering talent to real industry opportunities.
Watch the video: