Business
Oil Price Sinks to 17 Years All Time Low at $24

- /home/rhoncare/pointblank.ng/wp-content/plugins/mvp-social-buttons/mvp-social-buttons.php on line 27
https://pointblank.ng/wp-content/uploads/2020/03/Crude-Oil.jpg&description=Oil Price Sinks to 17 Years All Time Low at $24', 'pinterestShare', 'width=750,height=350'); return false;" title="Pin This Post">
- Share
- Tweet /home/rhoncare/pointblank.ng/wp-content/plugins/mvp-social-buttons/mvp-social-buttons.php on line 69
https://pointblank.ng/wp-content/uploads/2020/03/Crude-Oil.jpg&description=Oil Price Sinks to 17 Years All Time Low at $24', 'pinterestShare', 'width=750,height=350'); return false;" title="Pin This Post">
The price of Brent crude, the international benchmark, tumbled on Wednesday to the lowest level in 17 years as global markets continued to respond to the price war between Saudi Arabia and Russia amid the spread of the coronavirus pandemic.
Brent, against which Nigeria’s crude is priced, fell by $3.84 to $24.89 per barrel as of 7.05 pm Nigerian time on Wednesday, its lowest level since late 2002.
With the oil price now more than 50 per cent lower than Nigeria’s budget benchmark, the country’s oil-dependent economy has come under more pressure.
The 2020 budget, which was signed by the President, Major General Muhammadu Buhari (retd.), in December, was based on oil production of 2.18 million barrels per day with an oil price benchmark of $57 per barrel.
The Federal Government was looking to generate N2.64tn oil revenue, representing 32.34 per cent of expected total revenue for this year, with non-oil revenue projection being N1.80tn.
The price war between Saudi Arabia, the de facto leader of the Organisation of Petroleum Exporting Countries, and Russia after the collapse of talks on coordinated output cuts is increasing pressure on the market, according to Reuters.
Travel and social lockdowns aimed at countering the coronavirus were said to have raised prospect of the steepest ever annual fall in oil demand.
Investment banks and consultancies have been making heavy cuts to their demand forecasts as a growing number of the world’s largest cities and economies restrict movement.
“The oil demand collapse from the spreading coronavirus looks increasingly sharp,” Goldman Sachs said in a note, forecasting a fall in Brent prices to as low as $20 in the second quarter, a level not seen since early 2002.
The bank expects a demand contraction of eight million barrels per day by late March and an annual decline in 2020 of 1.1 million bpd, which it said would be the biggest on record.
Rystad Energy has gone even further, projecting a year-on-year decline in demand of 2.8 million bpd, or 2.8 per cent, this year.
“To put the number into context, last week we projected a decrease of just 600,000 barrels,” Rystad said.
In addition to imposing social restrictions not seen since World War Two, the world’s richest nations prepared to unleash trillions of dollars of spending to reduce the fallout from the coronavirus.
The impact on demand is starting to show in official statistics, with Japan’s trade bureau saying on Wednesday that crude imports into the world’s third-biggest economy in February were down nine per cent from a year earlier.
Virgin Australia became the latest airline to shut its international network with the suspension of all overseas flights, while the Australian Prime Minister, Scott Morrison, warned that the situation could last six months or more.
Elsewhere, Iraq’s oil minister pleaded for an emergency meeting between members of OPEC and non-OPEC producers to discuss immediate action to support the market.
Saudi Arabia’s energy ministry, however, said it had directed its national oil company, Saudi Aramco, to continue to supply crude oil at a record high 12.3 million bpd over the coming months.
Iraq’s Oil Minister, Thamer al-Ghadhban, asked OPEC to help to instigate urgent extraordinary meetings of the broader OPEC+ group, which includes Russia, to “discuss all possible ways” to rebalance the market.
The Punch


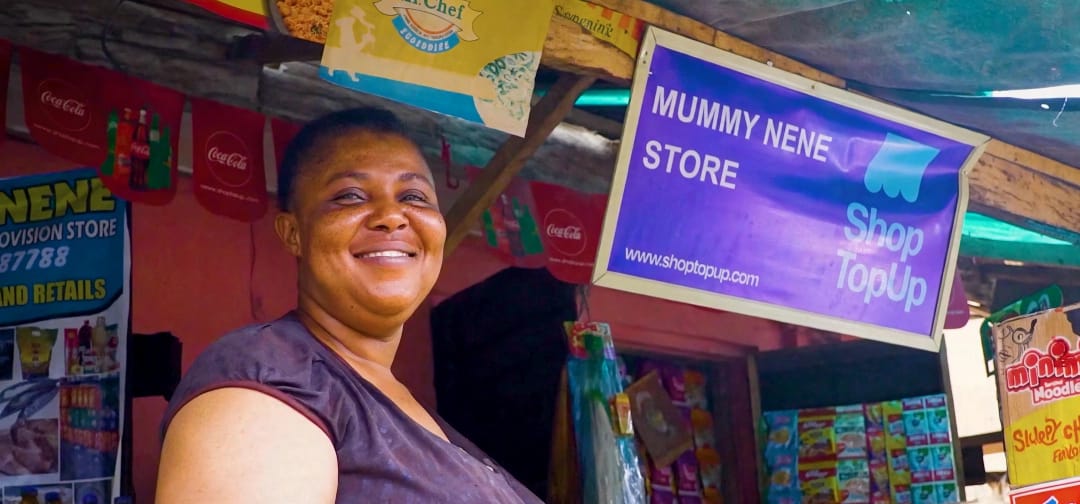
While conversations about the future of retail increasingly focus on supermarkets, shopping malls and online shopping platforms, millions of African consumers continue to rely on a more familiar and accessible business: the neighbourhood shop.
From small provision stores and corner shops to kiosks and informal retailers, these businesses remain an important part of everyday commerce, connecting communities to essential household products. However, behind their convenience lies a supply chain challenge that often limits their growth.
For many small retailers, sourcing products, managing inventory and securing enough working capital to keep their shelves stocked can be difficult. Fragmented distribution networks, multiple intermediaries and limited access to financing often make it harder for them to compete and expand.
Technology is beginning to offer a different possibility.
Digital platforms can simplify the way neighbourhood retailers purchase goods by connecting them more directly with manufacturers and distributors. They can streamline ordering, improve product availability and make inventory management more efficient.
Access to financial technology can further strengthen these businesses by helping eligible retailers secure the working capital required to replenish stock, respond to customer demand and grow sustainably.
One Nigerian technology company working to address these challenges is TradeDepot, which is using digital innovation to connect small retailers with manufacturers and distributors.
By making product sourcing and distribution more efficient, the company is helping to address some of the longstanding barriers facing small businesses in Africa’s retail sector.
However, scaling technology-driven solutions across a fragmented retail market requires more than innovation. It also demands significant investment.
This is where development finance and venture capital become important.
Through Boost Africa, the European Investment Bank (EIB) invested in Partech Africa Fund, a venture capital fund that subsequently backed TradeDepot. The investment illustrates how development finance can reach innovative African businesses through investment funds, providing capital to companies working to solve real economic challenges.
Boost Africa is a joint initiative of the European Investment Bank and the African Development Bank, with support from the European Union. The initiative supports African businesses and strengthens the continent’s entrepreneurial ecosystem by improving access to finance and opportunities for growth.
The wider significance of this investment goes beyond the technology platform itself. Strengthening neighbourhood retailers can contribute to more efficient supply chains, support small business growth and improve access to everyday consumer goods across communities.
For Africa, where small retailers remain central to local economies, the opportunity is substantial.
The future of retail may not necessarily involve replacing traditional neighbourhood shops with large supermarkets or online marketplaces. Instead, it could depend on equipping these existing businesses with better technology, stronger distribution networks and improved access to finance.
Ultimately, transforming retail may begin with something as familiar as the shop around the corner.
Boost Africa: From Capital to Impact.
Watch how TradeDepot is bringing commerce closer to communities through technology and investment
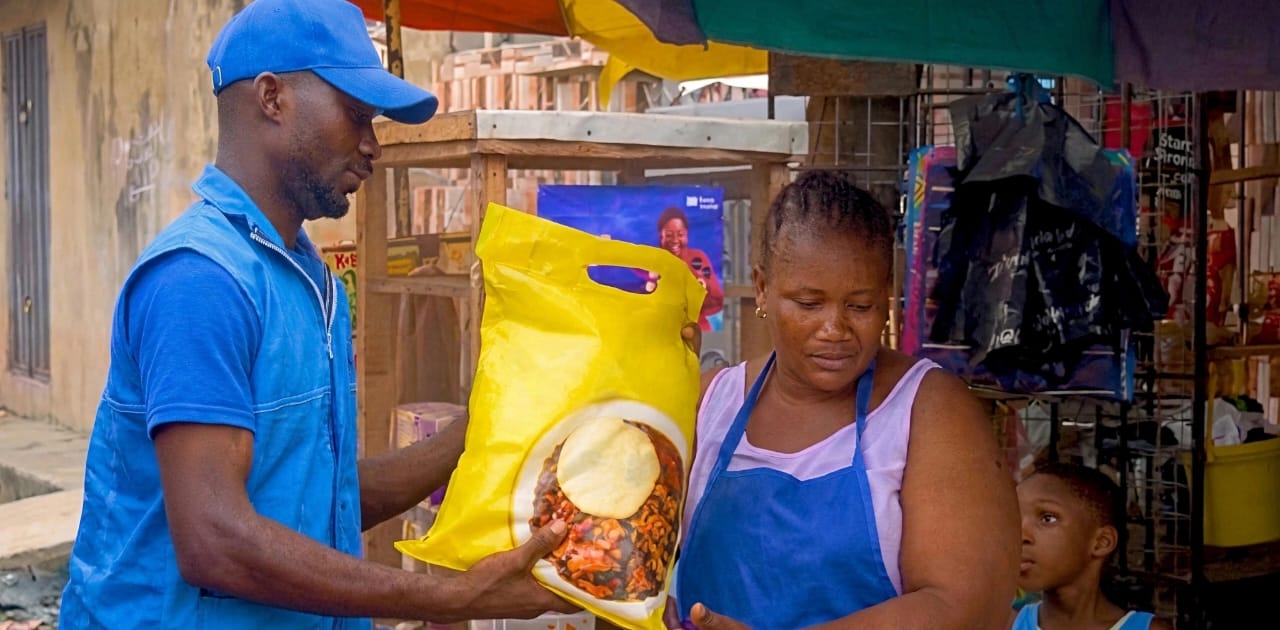
Ever wondered how the products on your neighbourhood shop shelves get there? Behind everyday purchases is a supply chain that can be costly, complex and inefficient, particularly for small retailers.
Nigerian technology company TradeDepot is changing this process by using technology to connect small retailers with manufacturers and distributors, making it easier for shop owners to order and receive the goods they need.
But transforming retail distribution takes more than an innovative idea. It requires investment to build, expand and scale.
Through Boost Africa, the European Investment Bank (EIB), alongside the African Development Bank and with support from the European Union, is helping strengthen the financing ecosystem for innovative African businesses.
One example is the EIB’s investment in Partech Africa Fund, which subsequently backed TradeDepot, helping channel capital into a Nigerian business working to improve how goods move from suppliers to neighbourhood shops.
The impact goes beyond technology. More efficient distribution can help small retailers access inventory, strengthen connections between manufacturers and suppliers, and bring commerce closer to the communities they serve.
Ultimately, TradeDepot’s story demonstrates how investment can go beyond funding to support stronger businesses, more efficient markets and opportunities for small retailers.
Boost Africa: From Capital to Impact.
Watch how TradeDepot is bringing commerce closer to communities.
▶ https://www.youtube.com/watch?v=zw9t2asF9Pc
Business
Beyond University Degrees: How ChipMango is Preparing African Engineers for Global Tech Industry
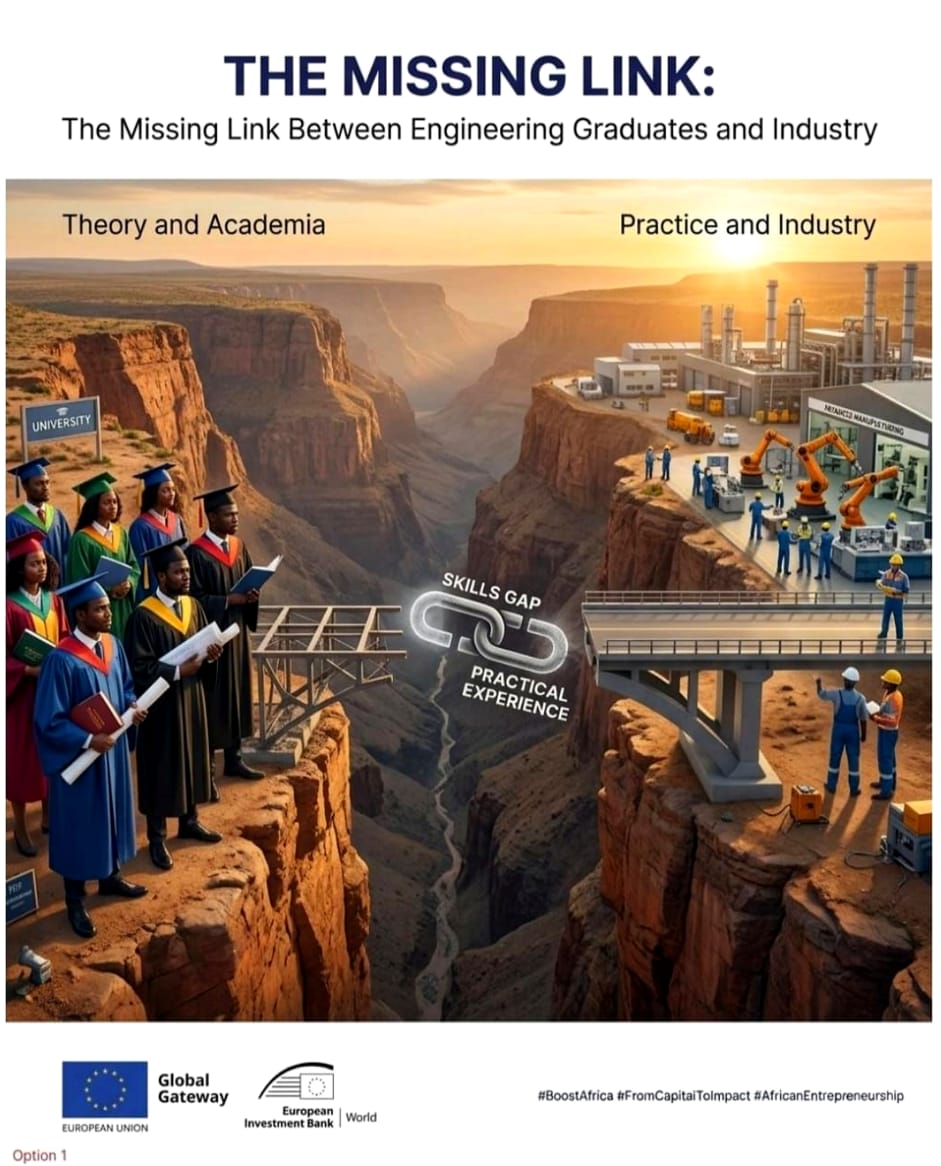
A university degree is a starting point, but practical industry experience can make all the difference.
Nigerian technology company ChipMango is bridging the gap through specialised semiconductor training and real-world chip design and verification projects, preparing African engineers for opportunities in the global technology industry.
Through Boost Africa, the EIB, AfDB and EU are strengthening the investment ecosystem supporting innovative African businesses.
Watch the video to discover how ChipMango is connecting engineering talent to real industry opportunities.
Watch the video: