Business
Unity Bank Sustains Momentum, As Profits Rise by 43% in Q1/2021

- /home/rhoncare/pointblank.ng/wp-content/plugins/mvp-social-buttons/mvp-social-buttons.php on line 27
https://pointblank.ng/wp-content/uploads/2021/04/IMG-20210412-WA0161.jpg&description=Unity Bank Sustains Momentum, As Profits Rise by 43% in Q1/2021', 'pinterestShare', 'width=750,height=350'); return false;" title="Pin This Post">
- Share
- Tweet /home/rhoncare/pointblank.ng/wp-content/plugins/mvp-social-buttons/mvp-social-buttons.php on line 69
https://pointblank.ng/wp-content/uploads/2021/04/IMG-20210412-WA0161.jpg&description=Unity Bank Sustains Momentum, As Profits Rise by 43% in Q1/2021', 'pinterestShare', 'width=750,height=350'); return false;" title="Pin This Post">
Nigeria’s foremost agric lender, Unity Bank Plc has sustained the growth momentum demonstrated in its 2020 full year earnings as it recorded an impressive performance of 43% in both profit before and after tax in Q1-2021.
In the Bank’s unaudited Q1-2021 results submitted to the Nigerian Stock Exchange on Friday, the retail lender’s Profit Before Tax grew by 43% to N784.3million from N550.1 million recorded in the corresponding period of 2020.
The Profit After Tax for the period which also grew by 43% stood at N721.5million compared to the N506.1million recorded in Q1-2020.
As an outcome of increased focus on supporting local enterprises and industry, the asset portfolio also showed a significant growth in loan book of 76% as net loans and advances to customers increased to N223.2billion up from N126.6billion recorded in the corresponding period.
The total assets of the Bank for the period showed an appreciable growth of 42% to close at N521.5 billion from N366.8 billion in the corresponding period of 2020. The balance sheet of the bank had been considerably de-risked with an NPL ratio of near zero per cent (0%) which it had consistently maintained over time, thus making the Bank to rank as one of the best in risk management and credit creation culture.
The Bank recorded gross earnings of N11.5billion, representing marginal decline of 3% when compared to N11.9billion posted in the corresponding period of 2020. The remarkable positive growth in profit and other strong indicators recorded in Q1-2021 is a sign of the Bank’s growing resilience as the economy continues on a recovery path following the impacts of COVID-19 pandemics.
Other key highlights of the Q1-2021 results included the cash and balances with the Central Bank which recorded a whopping 326% leap to close at N111.2billion from N26.1billion in the corresponding period of 2020.
The lender also grew its customer deposits by 13% to N348.3billion up from N308.8billion recorded in the period under review, a strong indication of the growing popularity and acceptance of the Bank’s array of innovative products and services and the arrays of new technologies deployed in its operations to enhance high level of customers’ experience and service delivery.
Interest and similar income also recorded a marginal increase of 1% to N9.7billion compared to N9.6 billion posted in the corresponding quarter of 2020. However, net interest income recorded a 16% increase to N4.8billion from N4.1billion in the corresponding period of 2020.
Total operating income also rose by 3% to N6.6billion from N6.4billion, even as the net operating income rose by 12% to close at N6.7billion from N5.9billion in the corresponding period of 2020.
Commenting on the result, the Managing Director/CEO, Unity Bank Plc, Mrs. Tomi Somefun said that the first quarter result is a promising indication of better outcome for the year, profoundly reflecting the Bank’s renewed focus on driving efficiency and productivity anchored on targeted initiatives to grow both volume and quality of assets and offer a wide range of customer-centric products supported by novel technologies to its teeming and growing customers in all the six-geopolitical zones in Nigeria.
The top-line performance was driven by improvement in net interest income margins which reported 16% growth. To this, Mrs. Somefun stated the Bank’s is replicating the same momentum in the area of liability generation and to gain traction, “we are targeting opportunities across regions and identified segments in retail and SMEs whilst optimising our technology and digital platforms such as Omni-channel UniFi, USSD *7799# to deliver bundled product bouquet, operational efficiency and improved unparalleled customer service delivery. Like the multi-language service channels, customers are to expect more innovations as the year unfolds”.
Looking ahead, the Unity Bank’s Chief further stated: “The Bank will consolidate on the gains it has made on its assets growth and further build the franchise of the brand in many areas of the business to shake off any lethargy to galvanize efficiency across its earning assets, thereby diversifying its earnings base to further grow the bottom-line”.
The Bank will thus continue to play formidably and efficiently in the area of its strength especially in the niche space of agribusiness to get more involved in the value chain banking having firmly established its strong foothold in the financing of primary crop production such as rice, maize, cotton, wheat, sorghum, etc. coupled with their rich and robust structures in value creation. In her words, “we hope to continue to expand on this as we play our part in driving the nations’s quest for self-sufficiency in food production, employment generation, foreign exchange conservation and all allied advantages that come with agribusiness.”
Analysts commend the Q1-2021 result for the strong fundamentals and for the positive outlook in the future, even as market confidence continues to reflect encouraging momentum and the steady growth of the Bank’s balance sheet.


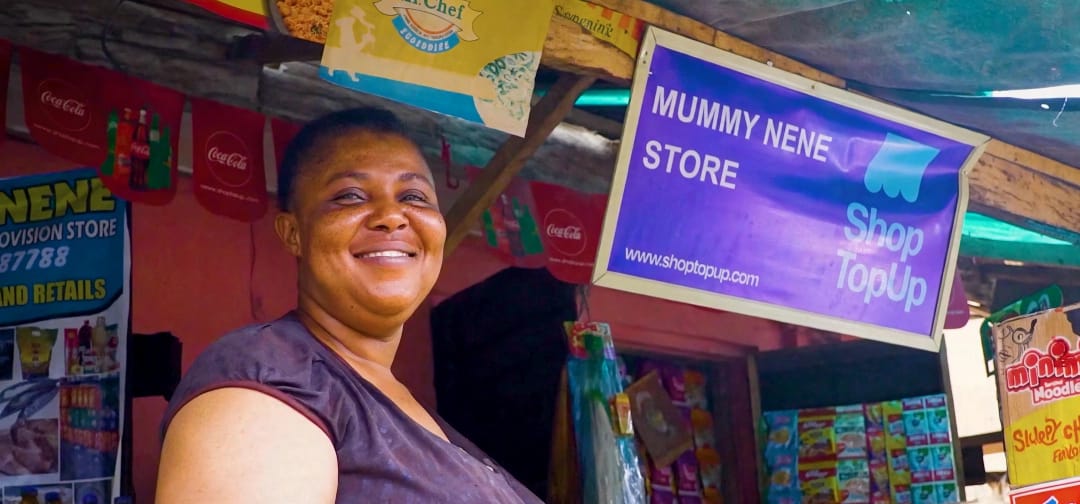
While conversations about the future of retail increasingly focus on supermarkets, shopping malls and online shopping platforms, millions of African consumers continue to rely on a more familiar and accessible business: the neighbourhood shop.
From small provision stores and corner shops to kiosks and informal retailers, these businesses remain an important part of everyday commerce, connecting communities to essential household products. However, behind their convenience lies a supply chain challenge that often limits their growth.
For many small retailers, sourcing products, managing inventory and securing enough working capital to keep their shelves stocked can be difficult. Fragmented distribution networks, multiple intermediaries and limited access to financing often make it harder for them to compete and expand.
Technology is beginning to offer a different possibility.
Digital platforms can simplify the way neighbourhood retailers purchase goods by connecting them more directly with manufacturers and distributors. They can streamline ordering, improve product availability and make inventory management more efficient.
Access to financial technology can further strengthen these businesses by helping eligible retailers secure the working capital required to replenish stock, respond to customer demand and grow sustainably.
One Nigerian technology company working to address these challenges is TradeDepot, which is using digital innovation to connect small retailers with manufacturers and distributors.
By making product sourcing and distribution more efficient, the company is helping to address some of the longstanding barriers facing small businesses in Africa’s retail sector.
However, scaling technology-driven solutions across a fragmented retail market requires more than innovation. It also demands significant investment.
This is where development finance and venture capital become important.
Through Boost Africa, the European Investment Bank (EIB) invested in Partech Africa Fund, a venture capital fund that subsequently backed TradeDepot. The investment illustrates how development finance can reach innovative African businesses through investment funds, providing capital to companies working to solve real economic challenges.
Boost Africa is a joint initiative of the European Investment Bank and the African Development Bank, with support from the European Union. The initiative supports African businesses and strengthens the continent’s entrepreneurial ecosystem by improving access to finance and opportunities for growth.
The wider significance of this investment goes beyond the technology platform itself. Strengthening neighbourhood retailers can contribute to more efficient supply chains, support small business growth and improve access to everyday consumer goods across communities.
For Africa, where small retailers remain central to local economies, the opportunity is substantial.
The future of retail may not necessarily involve replacing traditional neighbourhood shops with large supermarkets or online marketplaces. Instead, it could depend on equipping these existing businesses with better technology, stronger distribution networks and improved access to finance.
Ultimately, transforming retail may begin with something as familiar as the shop around the corner.
Boost Africa: From Capital to Impact.
Watch how TradeDepot is bringing commerce closer to communities through technology and investment
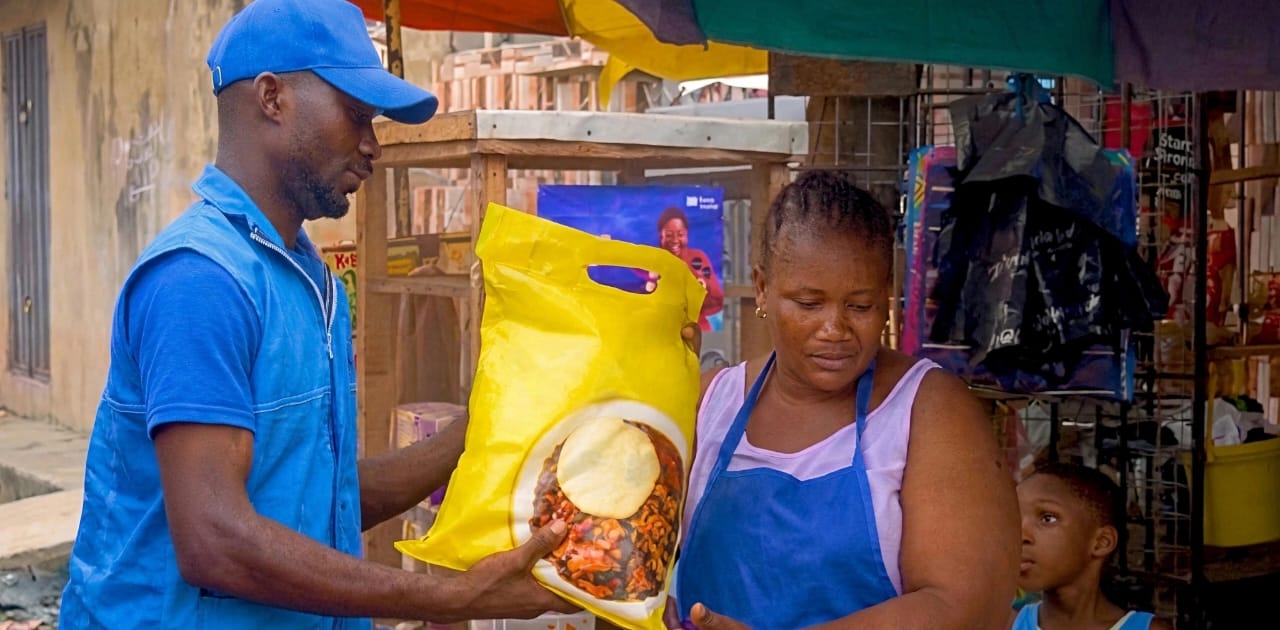
Ever wondered how the products on your neighbourhood shop shelves get there? Behind everyday purchases is a supply chain that can be costly, complex and inefficient, particularly for small retailers.
Nigerian technology company TradeDepot is changing this process by using technology to connect small retailers with manufacturers and distributors, making it easier for shop owners to order and receive the goods they need.
But transforming retail distribution takes more than an innovative idea. It requires investment to build, expand and scale.
Through Boost Africa, the European Investment Bank (EIB), alongside the African Development Bank and with support from the European Union, is helping strengthen the financing ecosystem for innovative African businesses.
One example is the EIB’s investment in Partech Africa Fund, which subsequently backed TradeDepot, helping channel capital into a Nigerian business working to improve how goods move from suppliers to neighbourhood shops.
The impact goes beyond technology. More efficient distribution can help small retailers access inventory, strengthen connections between manufacturers and suppliers, and bring commerce closer to the communities they serve.
Ultimately, TradeDepot’s story demonstrates how investment can go beyond funding to support stronger businesses, more efficient markets and opportunities for small retailers.
Boost Africa: From Capital to Impact.
Watch how TradeDepot is bringing commerce closer to communities.
▶ https://www.youtube.com/watch?v=zw9t2asF9Pc
Business
Beyond University Degrees: How ChipMango is Preparing African Engineers for Global Tech Industry
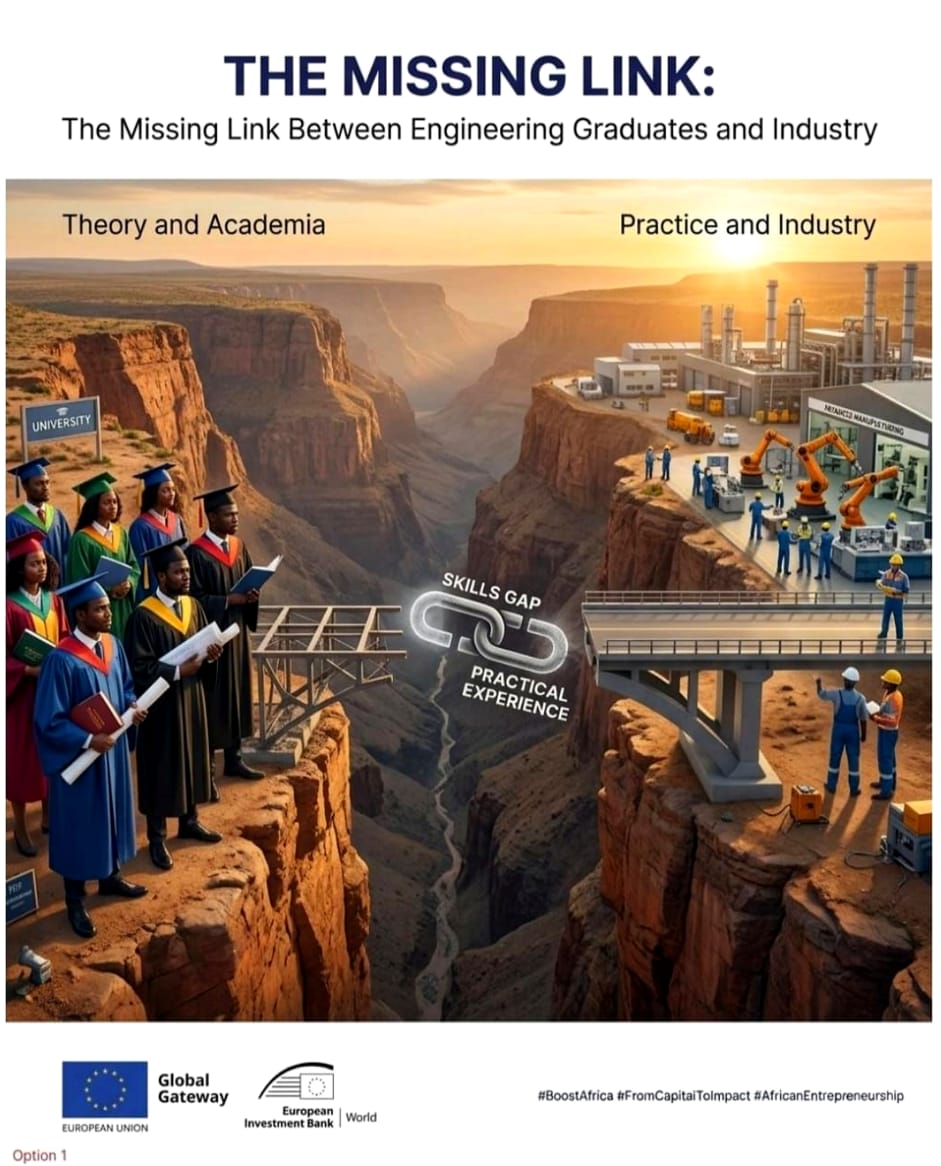
A university degree is a starting point, but practical industry experience can make all the difference.
Nigerian technology company ChipMango is bridging the gap through specialised semiconductor training and real-world chip design and verification projects, preparing African engineers for opportunities in the global technology industry.
Through Boost Africa, the EIB, AfDB and EU are strengthening the investment ecosystem supporting innovative African businesses.
Watch the video to discover how ChipMango is connecting engineering talent to real industry opportunities.
Watch the video: