Business
COVID-19: FirstBank Keeps Faith with Customers, Stays Ahead

- /home/rhoncare/pointblank.ng/wp-content/plugins/mvp-social-buttons/mvp-social-buttons.php on line 27
https://pointblank.ng/wp-content/uploads/2020/03/Dr.-Adesola-Adeduntan-FirstBank-CEO-1000x600.jpg&description=COVID-19: FirstBank Keeps Faith with Customers, Stays Ahead', 'pinterestShare', 'width=750,height=350'); return false;" title="Pin This Post">
- Share
- Tweet /home/rhoncare/pointblank.ng/wp-content/plugins/mvp-social-buttons/mvp-social-buttons.php on line 69
https://pointblank.ng/wp-content/uploads/2020/03/Dr.-Adesola-Adeduntan-FirstBank-CEO-1000x600.jpg&description=COVID-19: FirstBank Keeps Faith with Customers, Stays Ahead', 'pinterestShare', 'width=750,height=350'); return false;" title="Pin This Post">
Amid shutting down of various activities, especially commercial services, through lockdown measures aimed at containing the coronavirus pandemic, FirstBank has proven that as long as its customers require services, they will be served, and satisfactorily.
As key enablers of the economy, banks are providers of essential services to customers and communities.
Sequel to the pandemic outbreak, the Minister of Finance, Budget and Planning and the Governor of the Central Bank of Nigeria obtained Presidential approval to permit critical financial services to function during this period.
CBN further urged the general public to limit their use of cash and avail themselves of alternative payment channels such as mobile banking, internet banking, mobile money, Point of Sale (POS), and USSD banking; assuring that financial institutions will remain operational during this period and therefore people should guard against panic withdrawals from their banks.
The assumption that banks will be able to deliver services during this period, was no doubt predicated on the fact that institutions like FirstBank already had a fully functional digital infrastructure, to serve its customers through electronic channels.
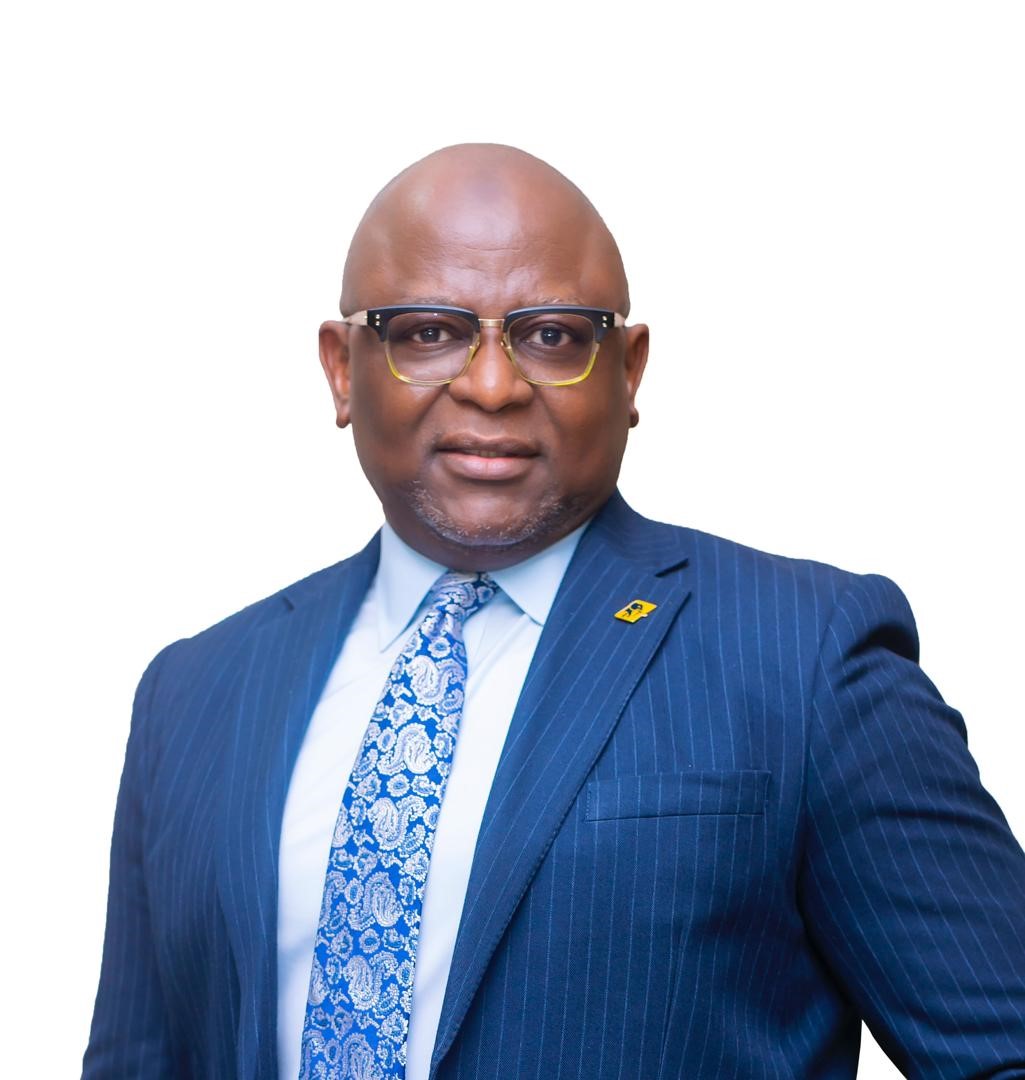
In a statement to customers, FirsBank’s CEO Dr. Adesola Adeduntan, categorically made this promise to them: “COVID-19 will not slow us down”.
“These are unprecedented times,” acknowledges Adeduntan “We therefore promise that now more than ever we will remain steadfast, showing up for all Nigerians; we would always be there for you.
“As I reflect on the last two weeks, I am comforted by the resilience of our people. I look back at our commitment and contribution to keeping commerce going and enabling businesses.”
These reassuring words of Dr. Adeduntan, do not go without tangible proofs of the bank’s unrelenting efforts to stay ahead of the situation many customers feared would cripple banking transactions and further exacerbate the pains brought on by the pandemic.
Indeed, since the enforcement of the lockdown measure, regular and unique ancillary services continue to be seamlessly delivered by FirstBank.
The impressive achievements of FirstBank in service delivery, during this unexpected disruption to lives and businesses on a global scale, has been nothing short of the extraordinary.
Or how would you explain over 53,000 agents bringing banking services right to your doorsteps, processing over 5 million transactions with different and large monetary values in the week preceding 10 April.
How about an approximate 2.5 million withdrawals amounting to N35billion across FirstBank’s ATMS in a single week?
On record, FirstBank’s larger corporate customers have done over 1,700 transactions successfully on the bank’s e-bills platform worth N6.8billion during this challenging period.
Nigerians with FirstBank cards have used them 21 million times for payments or withdrawals, worth N268 million.
Customers have made transfers over 10 million times with a total value of about N615billion naira across FirstBank’s digital channels all in one week.
How does a bank get all these done under the prevalent lockdown and disruption of regular routine?
“Expertise and resilience are in our DNA,” explains the Bank’s CEO, “we are working tirelessly to ensure that your banking transactions continue seamlessly and will remain so; COVID-19 will neither slow us down nor defeat us.
We are holding up our side, and now more than ever we will uphold our promise to you to be here for you and put You First.”
Indeed, the capability of banks to render uninterrupted digital services and investment advisory across many channels, especially during a crisis, projects economic stability.
More than ever before, the importance of the services banks provide to individuals and communities extends beyond commercial interests, especially now that cash withdrawals far outstrip deposits.
As an unprecedented challenge to financial institutions like banks, the current coronavirus pandemic serves as a litmus test for them to prove their role as systemic stabilizers, delivering services at least in part for social good.
As the crisis lingers with no end in sight, FirstBank staff remarkably are in place to attend to customers’ needs, in spite of the social distancing measure.
The bank continues to maintain all pre-existing channels of communication including receiving emails through its firstcontact@firstbanknigeria. com address and urging customers to contact their Relationship Managers or Private Bankers for banking services guidance and advisory.
Despite the extra efforts banks may put into rendering uninterrupted services in times like this, they are doing nothing more, than to meet the expectations of customers and maintain economic stability.
From a tactical level, financial institutions like banks can do a lot to reduce consumer and business stress, because as deposit gatherers, credit grantors, and payment facilitators, banks play a vital role in the functioning of the economy.
However, delivering solutions tailored to each individual customer at this critical time, also engenders trust and brand loyalty.
“We recognize our role in keeping the engine going, keeping society going and recognize further, it is our responsibility to remain at the forefront of this; true to our name and in keeping with the incontrovertible fact that we are fully woven into the fabric of society. Our unparalleled network and total coverage of this nation serve us all well at this time ensuring service across the country via our safe, user friendly and convenient alternative channels are available for you 24/7,” says Adeduntan.
While Nigeria is Africa’s largest economy, large portions of the economy are in the informal sector and depend constantly on cash movement.
As the financial consequences mainly for MSMES become more serious due to paucity of inflows, (some major players in the economy – oil, aviation and tourism too are not spared) people will expect their banks to look out for them and protect them from imminent financial catastrophe.
Indeed, bank clients would like to see the pandemic brought under containment as soon as possible, in order to resume work and commercial activities. For them, a stable and reliable financial partner like FirstBank that has shown resilience and reliability would be an institution that can be leveraged on, to get business back on track and rolling as fast as possible, once this is over.
Adeduntan in concluding his statement says to the bank’s customers: “Rest assured that we are in this together, and together we will emerge stronger at the end of this period because this too shall pass. We have all it takes; your support, patronage and trust. We will always put You First”.


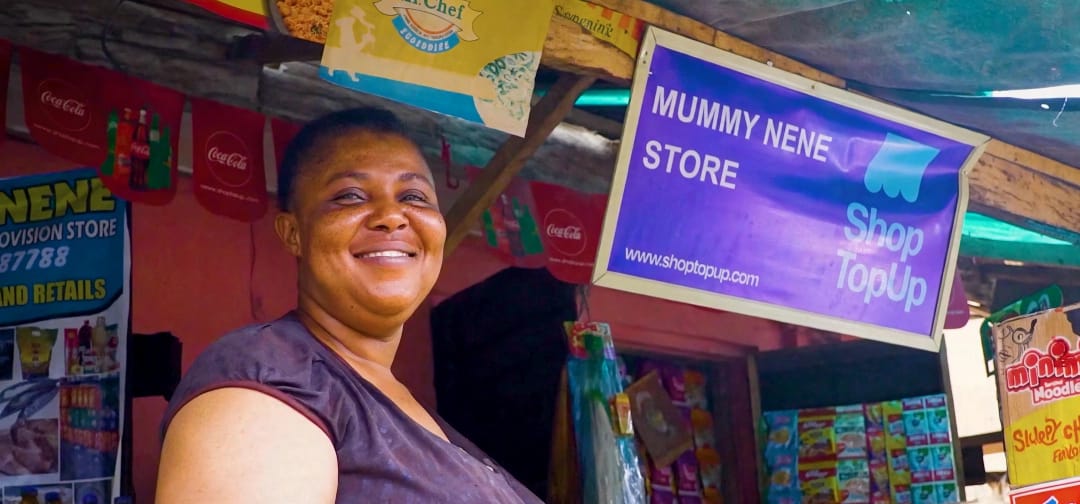
While conversations about the future of retail increasingly focus on supermarkets, shopping malls and online shopping platforms, millions of African consumers continue to rely on a more familiar and accessible business: the neighbourhood shop.
From small provision stores and corner shops to kiosks and informal retailers, these businesses remain an important part of everyday commerce, connecting communities to essential household products. However, behind their convenience lies a supply chain challenge that often limits their growth.
For many small retailers, sourcing products, managing inventory and securing enough working capital to keep their shelves stocked can be difficult. Fragmented distribution networks, multiple intermediaries and limited access to financing often make it harder for them to compete and expand.
Technology is beginning to offer a different possibility.
Digital platforms can simplify the way neighbourhood retailers purchase goods by connecting them more directly with manufacturers and distributors. They can streamline ordering, improve product availability and make inventory management more efficient.
Access to financial technology can further strengthen these businesses by helping eligible retailers secure the working capital required to replenish stock, respond to customer demand and grow sustainably.
One Nigerian technology company working to address these challenges is TradeDepot, which is using digital innovation to connect small retailers with manufacturers and distributors.
By making product sourcing and distribution more efficient, the company is helping to address some of the longstanding barriers facing small businesses in Africa’s retail sector.
However, scaling technology-driven solutions across a fragmented retail market requires more than innovation. It also demands significant investment.
This is where development finance and venture capital become important.
Through Boost Africa, the European Investment Bank (EIB) invested in Partech Africa Fund, a venture capital fund that subsequently backed TradeDepot. The investment illustrates how development finance can reach innovative African businesses through investment funds, providing capital to companies working to solve real economic challenges.
Boost Africa is a joint initiative of the European Investment Bank and the African Development Bank, with support from the European Union. The initiative supports African businesses and strengthens the continent’s entrepreneurial ecosystem by improving access to finance and opportunities for growth.
The wider significance of this investment goes beyond the technology platform itself. Strengthening neighbourhood retailers can contribute to more efficient supply chains, support small business growth and improve access to everyday consumer goods across communities.
For Africa, where small retailers remain central to local economies, the opportunity is substantial.
The future of retail may not necessarily involve replacing traditional neighbourhood shops with large supermarkets or online marketplaces. Instead, it could depend on equipping these existing businesses with better technology, stronger distribution networks and improved access to finance.
Ultimately, transforming retail may begin with something as familiar as the shop around the corner.
Boost Africa: From Capital to Impact.
Watch how TradeDepot is bringing commerce closer to communities through technology and investment
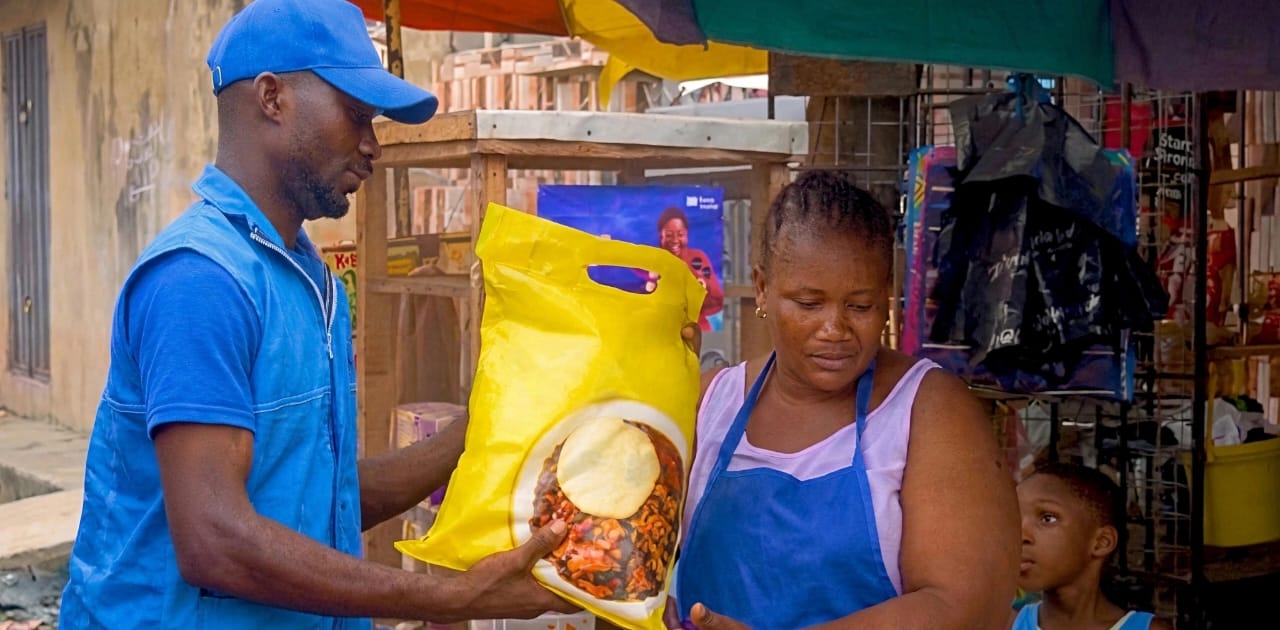
Ever wondered how the products on your neighbourhood shop shelves get there? Behind everyday purchases is a supply chain that can be costly, complex and inefficient, particularly for small retailers.
Nigerian technology company TradeDepot is changing this process by using technology to connect small retailers with manufacturers and distributors, making it easier for shop owners to order and receive the goods they need.
But transforming retail distribution takes more than an innovative idea. It requires investment to build, expand and scale.
Through Boost Africa, the European Investment Bank (EIB), alongside the African Development Bank and with support from the European Union, is helping strengthen the financing ecosystem for innovative African businesses.
One example is the EIB’s investment in Partech Africa Fund, which subsequently backed TradeDepot, helping channel capital into a Nigerian business working to improve how goods move from suppliers to neighbourhood shops.
The impact goes beyond technology. More efficient distribution can help small retailers access inventory, strengthen connections between manufacturers and suppliers, and bring commerce closer to the communities they serve.
Ultimately, TradeDepot’s story demonstrates how investment can go beyond funding to support stronger businesses, more efficient markets and opportunities for small retailers.
Boost Africa: From Capital to Impact.
Watch how TradeDepot is bringing commerce closer to communities.
▶ https://www.youtube.com/watch?v=zw9t2asF9Pc
Business
Beyond University Degrees: How ChipMango is Preparing African Engineers for Global Tech Industry
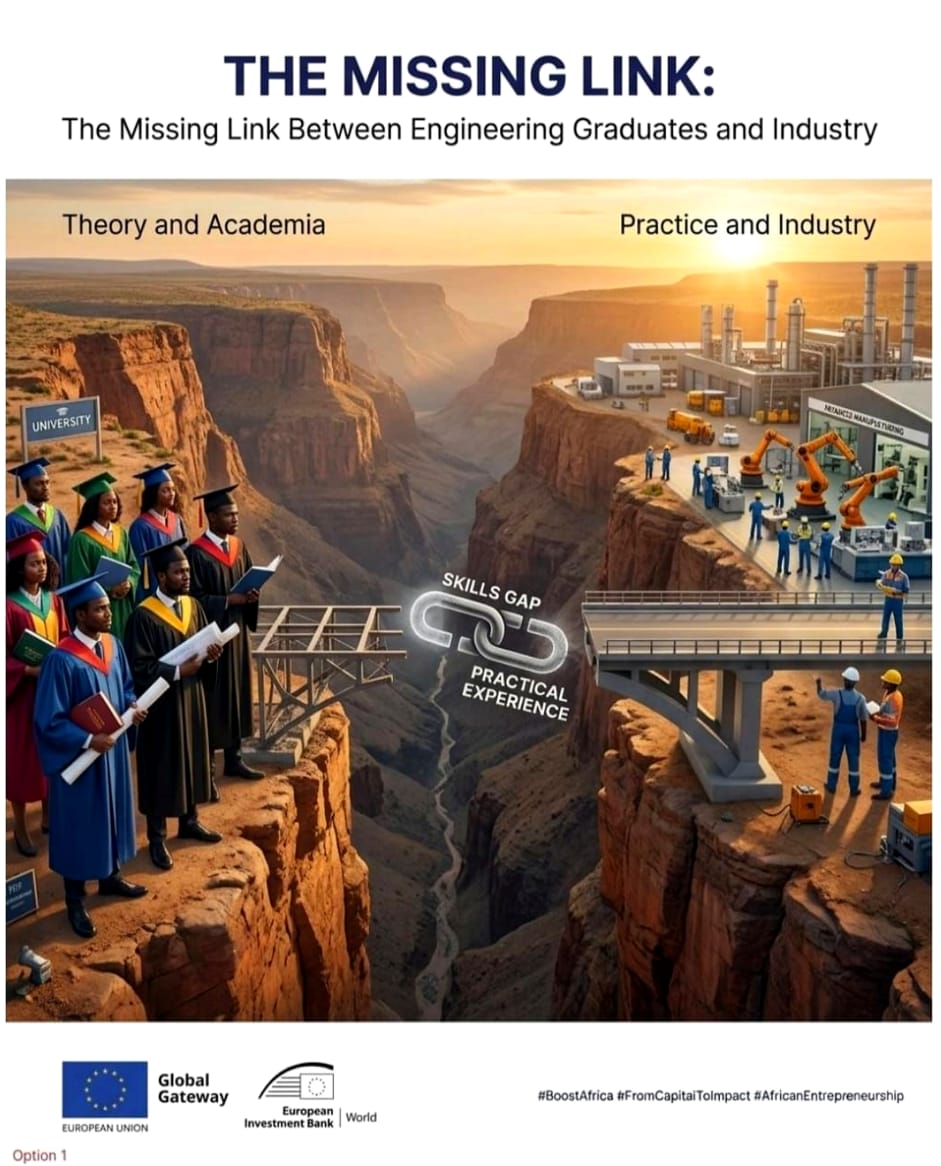
A university degree is a starting point, but practical industry experience can make all the difference.
Nigerian technology company ChipMango is bridging the gap through specialised semiconductor training and real-world chip design and verification projects, preparing African engineers for opportunities in the global technology industry.
Through Boost Africa, the EIB, AfDB and EU are strengthening the investment ecosystem supporting innovative African businesses.
Watch the video to discover how ChipMango is connecting engineering talent to real industry opportunities.
Watch the video: